

Interest Free Banking Powerpoint Presentation Slides Fin CD V





Try Before you Buy Download Free Sample Product
 Impress Your
Audience
 100%
Editable
 Save Hours
of Time


Check out our professionally designed Interest-Free Banking PowerPoint Presentation. Islamic Banking represents a financial system grounded in Islamic principles and values, offering an alternative approach to banking that emphasizes social and ethical responsibility while avoiding interest-based transactions. Islamic Banking, built on profit and loss sharing, strives for a more equitable financial framework. Our Islamic Banking Deck is an indispensable tool for individuals keen on understanding the principles and practices of Islamic Banking. It thoroughly examines key concepts, regulations, and instruments employed in Islamic Banking. The Sharia-compliant banking PowerPoint presentation covers diverse topics, including the prohibition of interest, risk-sharing, and the integral role of ethics in financial transactions. It further elucidates various modes of financing in Islamic Banking, such as Mudarabah, Musharakah, and Murabaha, among others. Additionally, our Ethical banking module provides clear and concise explanations, making it an ideal resource for those seeking a better understanding of Islamic Banking. Whether you are an aspiring banking professional, an entrepreneur, or simply curious about this expanding field, the Islamic Banking Deck is an essential resource that will enrich your comprehension and knowledge of Islamic Banking. Access it now.
People who downloaded this PowerPoint presentation also viewed the following :
Content of this Powerpoint Presentation
Slide 1: This slide introduces Interest-Free Banking. Commence by stating Your Company Name.
Slide 2: This slide depicts the Agenda of the presentation.
Slide 3: This slide includes the Table of contents.
Slide 4: This slide highlights the Title for the Topics to be discussed further.
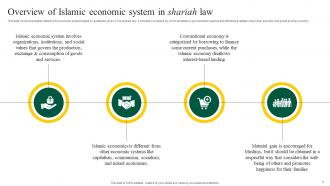
Slide 5: This slide presents the Overview of Islamic Economic System in Shariah law.
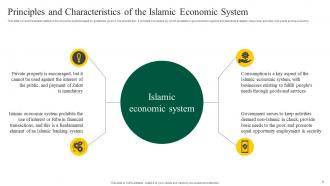
Slide 6: This slide states the Principles and Characteristics of the Islamic Economic System.
Slide 7: This slide covers the details related to the economic system based on guidelines given in the shariah law.
Slide 8: This slide shows the economic system based on guidelines given in the shariah law.
Slide 9: This slide contains the Heading for the Contents to be discsussed further.
Slide 10: This slide depicts the Overview of Islamic banking in Shariah law.
Slide 11: Thisb slide continues the Overview of Islamic banking in Shariah law.
Slide 12: This slide defines the principles and social responsibilities of Islamic banks.
Slide 13: This slide reveals the History of Islamic banking.
Slide 14: This slide covers the details related to Islamic banking as specified in Shariah or Islamic law.
Slide 15: This slide continues the History of Islamic banking.
Slide 16: This slide showcases the Principles and philosophy of Islamic banking.
Slide 17: This slide exhibits the Principles and philosophy of Islamic banking.
Slide 18: This slide continues the Principles and philosophy of Islamic banking.
Slide 19: This slide covers the details related to Islamic banking, a banking system that complies with Islamic law (shariah).
Slide 20: This slide defines the benefits of Islamic banking to its clients.
Slide 21: This slide defines the two concepts Riba and Gharar, of Islamic finance that are prohibited under Sharia law.
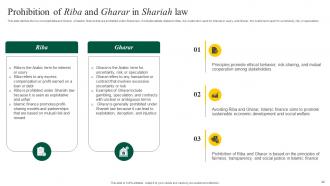
Slide 22: This slide talks about the Prohibition of Riba in Shariah law.
Slide 23: This slide defines the prohibition of Gharar, an essential aspect of Islamic finance that aims to promote fairness, transparency, and responsible business practices.
Slide 24: This slide continues the Prohibition of Gharar in Shariah law.
Slide 25: This slide depicts a flowchart representing Islamic banks’ transactions.
Slide 26: This slide highlights the Key differences between Islamic and conventional banking.
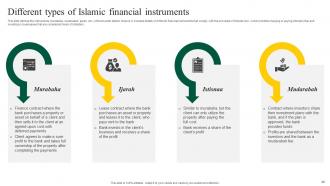
Slide 27: This slide states the Different types of Islamic financial instruments.
Slide 28: This slide continues the Different types of Islamic financial instruments.
Slide 29: This slide covers the details related to Islamic finance, a system of financial transactions that complies with Shariah law.
Slide 30: This slide portrays the Different types of Islamic banking model.
Slide 31: This slide defines Islamic finance and banking's external atmosphere based on the PESTEL analysis.
Slide 32: This slide continues the Islamic finance and banking PESTEL analysis.
Slide 33: This slide defines Islamic finance and banking’s internal and external atmosphere based on the SWOT analysis.
Slide 34: This slide talks about the Digital transformation in Islamic banking and financial institutions.
Slide 35: This slide continues the Digital transformation in Islamic banking and financial institutions.
Slide 36: This slide highlights the Title for the Ideas to be covered further.
Slide 37: This slide focuses on Comparing the governance structure of Islamic and conventional institutions.
Slide 38: This slide states the Differences between Conventional Bank and Islamic Bank.
Slide 39: This slide highlights the Differences between Conventional Bank and Islamic Bank.
Slide 40: This slide covers the details related to the differences between Islamic and conventional banking based on financial instruments.
Slide 41: This slide states the Differences between Conventional Bank and Islamic Bank.
Slide 42: This slide continues the Differences between Conventional Bank and Islamic Bank.
Slide 43: This slide portrays the Heading for the Ideas to be discussed next.
Slide 44: This slide exhibits the Modes of Islamic banking and financing in Shariah law.
Slide 45: This slide defines the different types of Islamic banking or Islamic finance which is a form of shariah (Islamic law)-compliant finance.
Slide 46: This slide presents the Applications of Islamic financial instruments in Shariah law.
Slide 47: This slide depicts the flowchart defining the process of transacting in Islamic financial instruments.
Slide 48: This slide states the Title for the Contents to be covered in the Upcoming template.
Slide 49: This slide covers the details related to the different categories of financial contracts offered by Islamic banks.
Slide 50: This slide shows the details related to the different categories of financial contracts offered by Islamic banks.
Slide 51: This slide presents the different categories of financial contracts offered by Islamic banks.
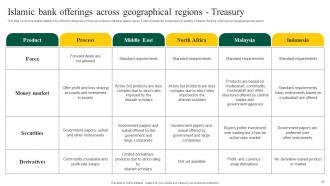
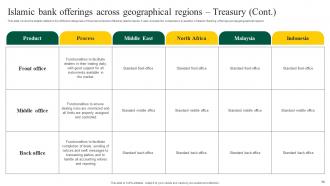
Slide 52: This slide displays the Islamic bank offerings across geographical regions.
Slide 53: This slide covers the details related to the different categories of financial contracts offered by Islamic banks.
Slide 54: This slide continues the different categories of financial contracts offered by Islamic banks.
Slide 55: This slide presents the details related to the different categories of financial contracts offered by Islamic banks.
Slide 56: This slide shows the different categories of financial contracts offered by Islamic banks.
Slide 57: This slide continues the Islamic bank offerings across geographical regions.
Slide 58: This slide portrays the different categories of financial contracts offered by Islamic banks.
Slide 59: This slide exhibits the Heading for the Topics to be discussed further.
Slide 60: This slide depicts the list of the largest Islamic banks based on their assets and net income.
Slide 61: EThis slide talks about the existence and presence of largest Islamic banks worldwide.
Slide 62: This slide defines the best Islamic financial institutions in the world for 2022.
Slide 63: This slide represents the best Islamic financial institutions in the world.
Slide 64: This slide continues the World’s best Islamic financial Institutions.
Slide 65: This slide defines the best Islamic financial institutions in the world.
Slide 66: This slide defines the best Islamic financial institutions in the world.
Slide 67: This slide continues the World’s best Islamic financial Institutions.
Slide 68: This slide presents the best Islamic financial institutions in the world.
Slide 69: This slide showcases the World’s best Islamic financial Institutions.
Slide 70: This slide continues the best Islamic financial institutions in the world.
Slide 71: This slide defines the best Islamic financial institutions in the world.
Slide 72: This slide states the best Islamic financial institutions in the world.
Slide 73: This slide continues the World’s best Islamic financial Institutions.
Slide 74: This slide defines the best Islamic financial institutions in the world.
Slide 75: This slide talks about the World’s best Islamic financial Institutions.
Slide 76: This slide continues the World’s best Islamic financial Institutions .
Slide 77: This slide defines the best Islamic financial institutions in the world.
Slide 78: This slide shows the World’s best Islamic financial Institutions.
Slide 79: This slide continues the World’s best Islamic financial Institutions.
Slide 80: This slide defines the best Islamic financial institutions in the world.
Slide 81: This slide presents the best Islamic financial institutions in the world.
Slide 82: This slide continues the best Islamic financial institutions in the world.
Slide 83: This slide defines the best Islamic financial institutions in the world.
Slide 84: This slide highlights the Title for the Topics to be covered in the upcoming template.
Slide 85: This slide exhibits the Role of Islamic banking and financial institutions.
Slide 86: This slide defines the role of Islamic banks in promoting Islamic financing.
Slide 87: This slide continues the Role of Islamic banking and financial institutions.
Slide 88: This slide presents the Role of Islamic financial institutions for economic growth.
Slide 89: This slide continues the Role of Islamic financial institutions for economic growth.
Slide 90: This slide covers the details related to Islamic banking.
Slide 91: This slide continues the Growth and development of Islamic banking industry globally.
Slide 92: This slide includes the Heading for the Contents to be discussed further.
Slide 93: This slide displays the Overview of Shariah law and its role in Islamic Banking.
Slide 94: This slide continues the Overview of Shariah law and its role in Islamic Banking.
Slide 95: This slide defines Shariah governance which is a mechanism adopted in Islamic financial institutions.
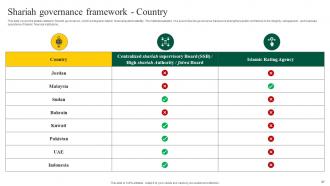
Slide 96: This slide covers the details related to Shariah governance, which is integral to Islamic financial system stability.
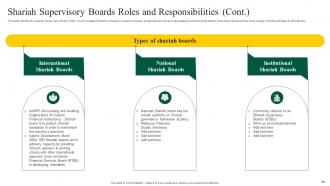
Slide 97: This slide presents Shariah Supervisory Boards Roles and Responsibilities.
Slide 98: This slide continues Shariah Supervisory Boards Roles and Responsibilities.
Slide 99: This slide defines the Shariah corporate governance institut.
Slide 100: This slide continues Shariah corporate governance institutions.
Slide 101: This slide depicts the supervisory boards managing the Islamic banks under the Shariah guidelines.
Slide 102: This slide shows the supervisory boards managing the Islamic banks under the Shariah guidelines.
Slide 103: This slide includes the Heading for the Contents to be covered in the next template.
Slide 104: This slide defines the opportunities of Islamic banking.
Slide 105: This slide exhibits the Challenges of Islamic banking and financial institutions.
Slide 106: This slide continues the Challenges of Islamic banking and financial institutions.
Slide 107: This slide depicts the global Islamic banking software market for the year 2020-2024.
Slide 108: This slide illustrates a table depicting the ranking of the strongest Islamic banks in the world for the year 2021.
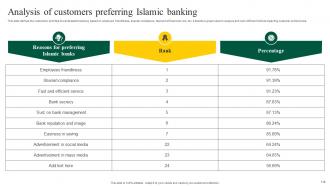
Slide 109: This slide defines the customers’ priorities towards Islamic banking.
Slide 110: This slide continues the Analysis of customers preferring Islamic banking.
Slide 111: This slide highlights the Global distribution of Islamic financial service.
Slide 112: This slide defines the global distribution of Islamic financial service industries based on different regions and segments.
Slide 113: This slide depicts the map highlighting the areas with the presence of Islamic banks.
Slide 114: This slide mentions the Global facts about Islamic banking.
Slide 115: This slide continues the Global facts about islamic banking.
Slide 116: This slide displays the future of Islamic banking and finance.
Slide 117: This slide continues the Future prospects of the islamic banking sector.
Slide 118: This slide shows the future of Islamic banking and finance.
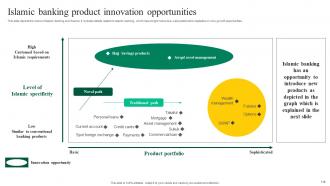
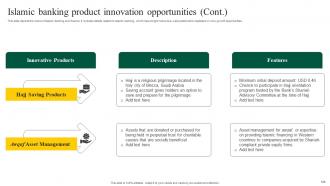
Slide 119: This slide continues the Islamic banking product innovation opportunities.
Slide 120: This is the Thank You slide for acknowledgement.
Interest Free Banking Powerpoint Presentation Slides Fin CD V with all 130 slides:
Use our Interest Free Banking Powerpoint Presentation Slides Fin CD V to effectively help you save your valuable time. They are readymade to fit into any presentation structure.































FAQs for Interest Free Banking Powerpoint Presentation Slides
So basically it's built around three main rules - no interest, no crazy uncertainty, and you can't invest in stuff like gambling or booze. Instead of fixed interest rates, you share the actual profits and losses, which honestly just feels more fair? Everything needs real assets backing it up, not just speculation. Both sides take on risk instead of one person getting guaranteed money while the other takes all the chances. Oh and if you're thinking about trying it out, maybe look into their profit-sharing accounts first - Islamic mortgages are pretty interesting too but that's probably jumping ahead.
So basically instead of charging interest, these banks do profit-sharing deals with you. You become partners where they share your business profits AND losses. Pretty smart actually - they're invested in your success too. They'll also do leasing or trade financing instead of regular loans. Just heads up though, even without "interest," their profit cut can end up costing about the same anyway lol. But yeah, it's all asset-backed stuff rather than just lending money and collecting interest payments.
So basically, sharia principles ban interest (they call it "riba"), which means Islamic banks can't just lend you money and charge fees like regular banks. Instead they do profit-sharing deals or buy assets and sell them to you at a markup. Pretty smart workaround honestly. Everything has to be backed by real stuff too - no sketchy paper trading. Oh, and they won't touch alcohol, gambling, or weapons investments. My cousin uses Islamic banking and says it's legit, just structured differently so the bank still makes money through partnerships with you instead of straight interest.
So basically you and the bank become actual business partners instead of the usual lender/borrower thing. With Mudarabah, you put up the money and they handle the investing - then you split whatever profits come in based on ratios you agreed on beforehand. If things go south though, you eat the financial loss while they just lose their time (which honestly seems fair enough). Musharakah works differently since both sides put in capital AND share any losses proportionally. The whole thing's pretty transparent from the start - no surprise fees or those sketchy "guaranteed returns" that banks love to push.
So basically you've got murabaha - they buy stuff and sell it to you with markup. Then there's ijara which is just Islamic leasing really. Musharaka is the profit-sharing one. Home financing gets weird though since no interest allowed, so it works totally different than regular mortgages. Most places have your standard current and savings accounts too. Oh and business investment stuff, trade financing. They get around the whole interest thing by doing asset ownership or leasing deals instead. Honestly depends where you are - some banks have way more options than others.
So basically, interest-free banking keeps things way more stable because your money gets tied to actual real stuff - like businesses and assets - instead of just debt gambling. Banks have to share the wins AND losses with borrowers, which makes them super picky about loans. No more of those crazy boom-bust cycles we always see. I mean, think about it - when everything's connected to tangible value instead of weird financial instruments, you don't get those overnight crashes that wipe people out. It's actually pretty smart.
Honestly? Regulatory stuff is a nightmare - every country has different compliance rules you've got to follow. Finding qualified people is brutal too. There just aren't enough Sharia-compliant scholars and bankers out there, which makes hiring a real pain. Liquidity gets messy since you can't touch interest-based instruments for quick funding. Traditional banks are breathing down your neck with simpler products and sometimes better rates. It's cutthroat. Dubai Islamic Bank figured this out pretty well though - might be worth checking how they handle the operational headaches if you're serious about this.
So basically, interest-free banks have to get creative since they can't just collect interest payments. They end up doing equity partnerships and funding actual stuff - solar farms, local businesses, that kind of thing. Way different from banks that just fuel speculation and trading nonsense. The whole model pushes them toward longer-term thinking too. Plus they're really into community projects and social impact stuff. Honestly makes more sense than traditional banking sometimes. If you're into sustainable finance, definitely look into Islamic banks or similar institutions doing profit-sharing instead of regular loans.
So it totally depends where you're looking to operate. Malaysia and UAE have solid Islamic banking frameworks already set up. The UK just tweaks their regular banking rules to make them Sharia-compliant. Pakistan's actually gone all-in and banned interest completely - which is pretty wild if you ask me. Singapore and Luxembourg are way more chill about it, they'll let regular banks run Islamic services on the side. The US? Still kind of a mess with barely any federal guidance. I'd definitely check what each country's central bank requires first since the rules are all over the place.
Muslims are your biggest market since they need Sharia-compliant options, but don't sleep on Christians and Jews who avoid interest too. Millennials and Gen Z love this stuff - fits their whole ethical spending thing. Small business owners often prefer profit-sharing over getting hit with loan interest, especially when cash flow's tight. Honestly, anyone who's been screwed by predatory lenders is pretty interested. Oh, and when you're pitching this, focus on the ethics and transparency. The "no interest" thing is obvious - people want to know it's actually legit and not some weird loophole situation.
So tech is basically revolutionizing Islamic banking right now. Apps can show profit-sharing calculations super clearly, and there's automated screening for Sharia-compliant investments. Digital sukuk trading platforms are popping up everywhere too. AI handles risk assessment without the whole interest thing - which honestly makes way more sense anyway. Blockchain's great for transparent transaction records, helps tons with compliance stuff. Robo-advisors can build you halal portfolios based on what risk you're comfortable with. I'd start by figuring out which fintech tools actually fit Islamic principles and see what streamlines your current setup.
Dude, the biggest myth is thinking interest-free means free money - you're still gonna pay fees and profit-sharing that sometimes costs MORE than regular interest. Wild, right? Lots of people assume it's just for religious reasons, but tons of folks pick it for ethical investing too. Oh and don't fall for the idea that these banks are sketchy or less regulated. They follow the same strict rules as regular banks, just different structures. My advice? Compare total costs before jumping in, not just whether they call it "interest" or something else.
So they basically flip the whole model - instead of interest, these banks use profit-sharing deals and asset-backed stuff. Like murabaha (cost-plus financing) and sukuk, which are kind of like Islamic bonds. Pretty smart actually. When they need cash between banks, they share profits and losses rather than paying fixed rates. The big difference? No guaranteed returns - everything's shared risk instead. Oh, and if you're ever looking at these banks (not sure why you would but whatever), check their asset quality and partnerships, not interest spreads like regular banks.
Yeah, interest-free banking is huge for financial inclusion! Removes that barrier for Muslim communities who won't touch interest-based stuff for religious reasons. Instead of the usual credit score obsession, they focus on asset-backed financing and profit-sharing - which honestly makes more sense to me. Community investment gets prioritized over sketchy speculation too. Oh, and it's not just Muslims - plenty of people have ethical issues with traditional interest models. If you're looking at inclusion strategies, definitely check out how Islamic banks structure everything. Way different approach but it works.
Yeah, they still check if you can actually pay them back - just differently. Instead of "can you afford this interest rate?" they're asking "can you handle these payments?" So they'll look at your income, debts, cash flow, assets, all that stuff. For business loans they really care about your actual plan too. The paperwork's pretty much the same honestly - financial statements, income proof, credit check. I think they focus more on your relationship with the bank than traditional ones do. Bottom line: they want to know you're financially solid, just without the interest piece.
-
I joined SlideTeam last month and there’s no doubt that I tend to find our bond only strengthening over time. Best place to find world-class themes, templates, and icons.
-
Presentation Design is very nice, good work with the content as well.