

Diapositivas de presentación de Powerpoint del plan comercial de servicios de seguros comerciales




Try Before you Buy Download Free Sample Product
 Impress Your
Audience
 100%
Editable
 Save Hours
of Time


Un plan comercial estratégico permite una hoja de ruta para desarrollar una empresa de seguros exitosa. Captura los objetivos de la empresa, las ofertas de productos, el mercado objetivo y las proyecciones financieras. Aquí hay una plantilla diseñada de manera competente sobre Servicios de seguros comerciales que desarrollará planes de negocios de inicio para agencias de seguros con elementos esenciales asociados con el plan de negocios. La plataforma ayudará a crear planes financieros, de marketing y de mano de obra para establecer una agencia de seguros. El desarrollo de un plan de negocios ayudará a establecer objetivos realistas, asignar recursos, optimizar los flujos de trabajo, mejorar la comunicación y la expansión del negocio. La plataforma cubre diapositivas sobre la descripción general de las empresas, el análisis del potencial de crecimiento en términos de análisis DAFO, análisis PESTLE, análisis de las cinco fuerzas de Porters, estrategia de comercialización, evaluación del mercado, grupos de clientes objetivo para el negocio de seguros, segmentación, posicionamiento de la empresa, etc. Presenta diapositivas sobre el plan de marketing en términos de la combinación de marketing del producto, la creación de marca y las estrategias publicitarias. La plataforma cubre diapositivas sobre la planificación del personal en términos de gestión de personal en agencias de seguros, capacitación de la fuerza laboral y hoja de ruta de desarrollo. Muestra diapositivas sobre la planificación financiera en términos de estados financieros proyectados, es decir, estados de resultados, balances, etc. Atiende a varios riesgos asociados con el tablero de seguimiento de negocios de seguros. Obtenga acceso a él ahora.
People who downloaded this PowerPoint presentation also viewed the following :
Contenido de esta presentación de Powerpoint
Diapositiva 1 : Esta diapositiva presenta el Plan comercial de servicios de seguros comerciales. Indique el nombre de su empresa y comience.
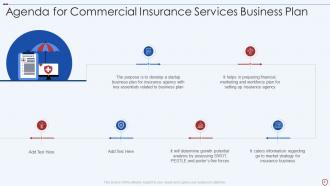
Diapositiva 2 : Esta diapositiva muestra la Agenda para el plan de negocios de servicios de seguros comerciales.
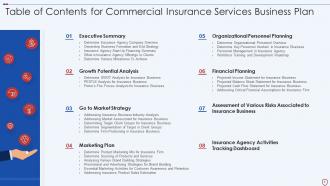
Diapositiva 3 : Esta diapositiva presenta el índice del plan comercial de servicios de seguros comerciales.
Diapositiva 4 : Esta diapositiva muestra la Tabla de contenido del Plan de negocios de servicios de seguros comerciales.
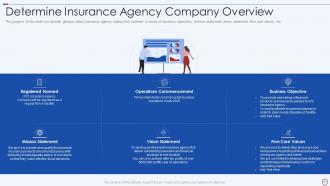
Diapositiva 5 : Esta diapositiva muestra la descripción general de Determinar la compañía de la agencia de seguros.
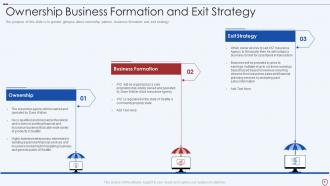
Diapositiva 6 : Esta diapositiva representa la formación de empresas de propiedad y la estrategia de salida.
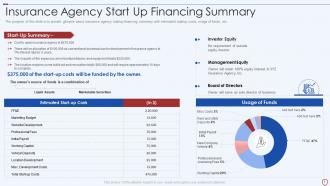
Diapositiva 7 : Esta diapositiva muestra el resumen de financiación inicial de una agencia de seguros.
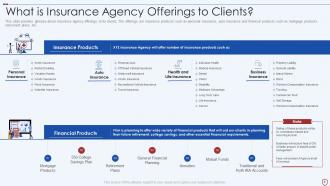
Diapositiva 8 : Esta diapositiva presenta las ofertas de las agencias de seguros a sus clientes.
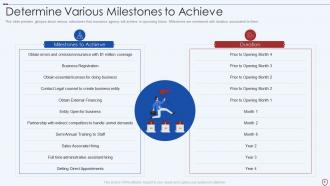
Diapositiva 9 : Esta diapositiva muestra varios hitos que la agencia de seguros alcanzará en el futuro próximo.
Diapositiva 10 : esta diapositiva muestra el índice del plan de negocios de servicios de seguros comerciales.
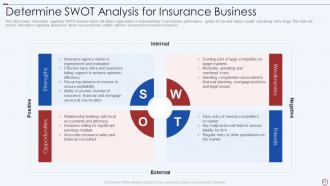
Diapositiva 11 : Esta diapositiva representa Determinar el análisis FODA para el negocio de seguros.
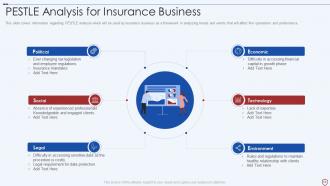
Diapositiva 12 : Esta diapositiva muestra el análisis PESTLE que será utilizado por el negocio de seguros como marco.
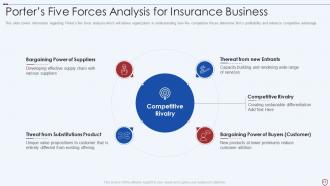
Diapositiva 13 : Esta diapositiva presenta el análisis de las cinco fuerzas de Porter para el negocio de seguros.
Diapositiva 14 : esta diapositiva muestra el índice del plan de negocios de servicios de seguros comerciales.
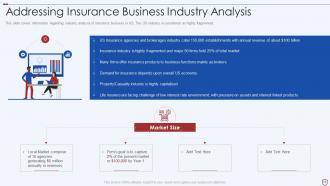
Diapositiva 15 : Esta diapositiva muestra el análisis de la industria del negocio de seguros en EE. UU.
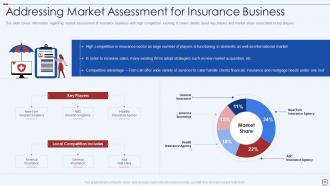
Diapositiva 16 : Esta diapositiva representa el abordaje de la evaluación del mercado para el negocio de seguros.
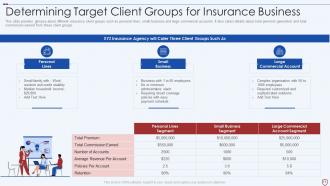
Diapositiva 17 : Esta diapositiva muestra la determinación de los grupos de clientes objetivo para el negocio de seguros.
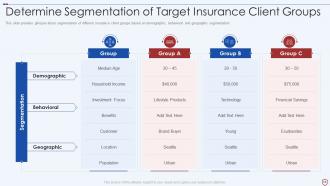
Diapositiva 18 : Esta diapositiva presenta Determinar la segmentación de los grupos objetivo de clientes de seguros.
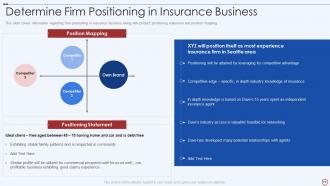
Diapositiva 19 : Esta diapositiva muestra Determinar el posicionamiento de la empresa en el negocio de seguros.
Diapositiva 20 : esta diapositiva muestra el índice del plan de negocios de servicios de seguros comerciales.
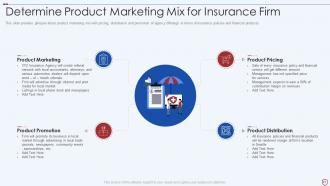
Diapositiva 21 : Esta diapositiva representa Determinar la mezcla de marketing de productos para la empresa de seguros.
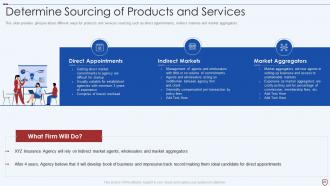
Diapositiva 22 : Esta diapositiva muestra Determinar el abastecimiento de productos y servicios.
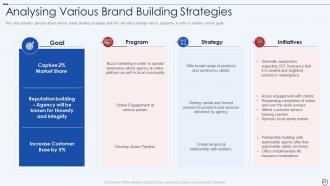
Diapositiva 23 : Esta diapositiva presenta el análisis de diversas estrategias de creación de marca.
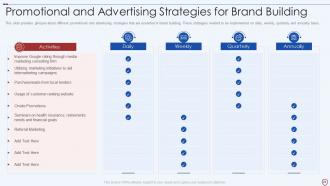
Diapositiva 24 : Esta diapositiva muestra estrategias promocionales y publicitarias para la construcción de marca.
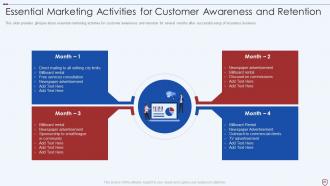
Diapositiva 25 : esta diapositiva muestra las actividades de marketing esenciales para la concientización y retención de clientes.
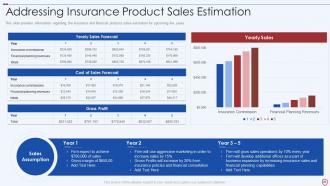
Diapositiva 26 : Esta diapositiva representa el abordaje de la estimación de ventas de productos de seguros.
Diapositiva 27 : esta diapositiva muestra el índice del plan de negocios de servicios de seguros comerciales.
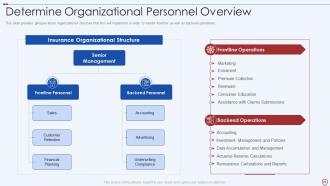
Diapositiva 28 : Esta diapositiva presenta la estructura organizativa que implementará la empresa para manejar la primera línea.
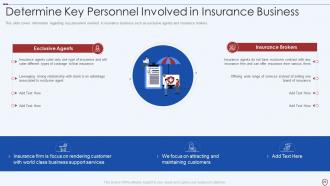
Diapositiva 29 : Esta diapositiva muestra Determinar el personal clave involucrado en el negocio de seguros.
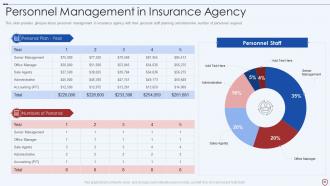
Diapositiva 30 : Esta diapositiva muestra la gestión de personal en la agencia de seguros con su planificación de personal personal.
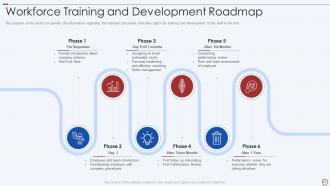
Diapositiva 31 : Esta diapositiva representa información sobre el procedimiento estándar que se lleva a cabo para la capacitación y el desarrollo.
Diapositiva 32 : Esta diapositiva presenta el índice del plan de negocios de servicios de seguros comerciales.
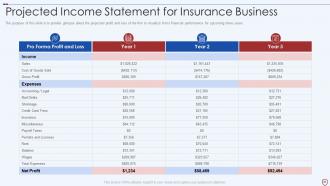
Diapositiva 33 : Esta diapositiva muestra el estado de resultados proyectado para el negocio de seguros.
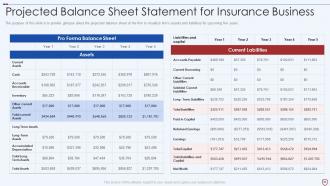
Diapositiva 34 : Esta diapositiva muestra el estado de situación financiera proyectado para el negocio de seguros.
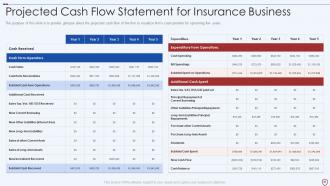
Diapositiva 35 : Esta diapositiva muestra el estado de flujo de efectivo proyectado para el negocio de seguros.
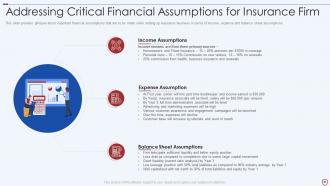
Diapositiva 36 : Esta diapositiva representa el abordaje de los supuestos financieros críticos para la empresa de seguros.
Diapositiva 37 : esta diapositiva muestra el índice del plan de negocios de servicios de seguros comerciales.
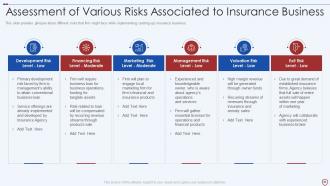
Diapositiva 38 : Esta diapositiva presenta la Evaluación de varios riesgos asociados al negocio de seguros.
Diapositiva 39 : esta diapositiva muestra el índice del plan de negocios de servicios de seguros comerciales.
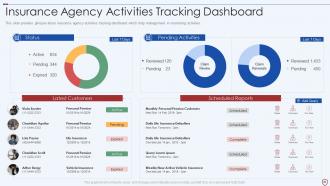
Diapositiva 40 : esta diapositiva muestra el panel de seguimiento de actividades de la agencia de seguros.
Diapositiva 41 : Esta diapositiva representa los íconos para el plan comercial de servicios de seguros comerciales.
Diapositiva 42 : esta diapositiva se titula Diapositivas adicionales para avanzar.
Diapositiva 43 : Esta diapositiva presenta un plan de 30 60 90 días con cuadros de texto.
Diapositiva 44 : esta diapositiva muestra la línea de tiempo semanal con el nombre de la tarea.
Diapositiva 45 : esta diapositiva muestra la hoja de ruta con cuadros de texto adicionales.
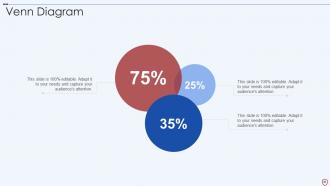
Diapositiva 46 : Esta diapositiva representa el diagrama de Venn con cuadros de texto.
Diapositiva 47 : Esta diapositiva muestra Post-It Notes. Publique sus notas importantes aquí.
Diapositiva 48 : Esta es la diapositiva Nuestro objetivo. Indique sus objetivos aquí.
Diapositiva 49 : Esta es una diapositiva de la línea de tiempo. Mostrar datos relacionados con los intervalos de tiempo aquí.
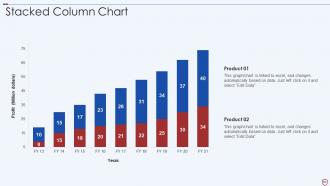
Diapositiva 50 : esta diapositiva muestra un gráfico de columnas apiladas con una comparación de dos productos.
Diapositiva 51 : Esta es una diapositiva financiera. Muestre sus cosas relacionadas con las finanzas aquí.
Diapositiva 52 : esta es una diapositiva de generación de ideas para exponer una nueva idea o resaltar información, especificaciones, etc.
Diapositiva 53 : Esta diapositiva presenta Puzzle con íconos y texto relacionados.
Diapositiva 54 : Esta es una diapositiva de agradecimiento con dirección, números de contacto y dirección de correo electrónico.
Diapositivas de presentación de Powerpoint del plan comercial de servicios de seguros comerciales con las 59 diapositivas:
Utilice nuestras diapositivas de presentación de Powerpoint del plan de negocios de servicios de seguros comerciales para ayudarlo de manera efectiva a ahorrar su valioso tiempo. Están listos para encajar en cualquier estructura de presentación.








FAQs for Commercial insurance services business plan
So general liability is for when you accidentally mess up someone else's day - like if they slip in your store or you damage their property while working. Property insurance covers YOUR stuff - building, equipment, inventory - from fires, theft, weather, whatever. You'll probably need both since they're totally different risks. The names actually make sense when you break it down... liability means you're on the hook for hurting others, property protects your own assets. Most brokers can bundle them together for less money. Worth asking about at least.
Start with calculating all your business stuff - equipment, inventory, property value, plus whatever liability risks come with your industry. Most places need enough property coverage to replace everything and liability that's like 2-3x annual revenue, but that's honestly just where you begin. A restaurant's gonna have way different risks than some consulting business, you know? Get quotes for different coverage amounts and see what the price jumps look like. Then find an agent who actually knows your industry - trust me, they'll catch stuff you never even thought about. Way better than trying to figure it out solo.
Your industry's the biggest factor - construction and manufacturing get hit way harder than something like consulting because of accident risks. Business size matters too (revenue, employee count), plus your claims history obviously. Location's huge - cities and disaster-prone areas cost more. Honestly, the whole system feels designed to squeeze you sometimes. Coverage limits and deductibles you pick will change your rate. Best ways to save: solid safety training for your team, shop around every year, and maybe bump up that deductible if you've got decent cash flow to cover it.
Yeah, absolutely! Insurance companies will cut you deals if they see you're not just hoping nothing bad happens. Get your employees trained on safety stuff and keep up with equipment maintenance - that's the bare minimum. Security cameras, fire systems, non-slip floors, all that protective gear can snag you discounts. Document everything you do safety-wise because insurers eat that up. Honestly, doing regular risk assessments is probably the smartest move since you'll catch problems before they cost you. Oh, and start with a safety audit to see where you're most vulnerable. Way better than dealing with claims later.
So business interruption insurance basically saves you when disasters force you to shut down - fires, storms, that kind of stuff. Lost income gets covered, plus ongoing expenses like rent and payroll. Sometimes they'll even pay extra costs to reopen faster. Here's the annoying part though: you have to prove what you would've made during the closure. Insurance companies are obsessed with documentation (shocking, I know). File your claim with detailed financial records showing normal revenue patterns. Oh, and start documenting literally everything the second something happens. Trust me, they'll ask for receipts on receipts.
So basically it's your backup when clients decide to blame you for stuff going wrong. Covers legal fees, settlements, all that expensive drama if they claim your work cost them money or wasn't up to standards. Like malpractice for doctors but for any professional - consultants, accountants, IT people, whatever. Honestly, even when you do everything right, clients will still point fingers sometimes. I learned this the hard way watching a friend deal with a nightmare client last year. You'll want to shop around though since different insurers have pretty different coverage options and prices.
Honestly, get yourself a good commercial insurance broker first - someone who actually knows your state's rules inside and out. They're expensive but totally worth it for this maze of requirements. You'll need the basic stuff like workers' comp and general liability at minimum levels, obviously. Keep those certificates up to date too. What I'd do is set up quarterly check-ins with your broker to spot problems early. Way better than scrambling later when something's already messed up. Oh, and put annual policy reviews on your calendar - especially when you're adding employees or expanding. That's usually when people get tripped up.
Honestly, the worst exclusions are pollution liability, cyber stuff, and professional liability - they'll totally screw you over. Watch out for the usual suspects too: intentional acts, criminal activity, war/terrorism (though some insurers are getting weird about terrorism coverage lately). Employment practices and product recalls are also commonly excluded. Business interruption gets tricky with natural disasters like floods and earthquakes. Here's the annoying part - every insurer does exclusions differently, so there's no standard list. Seriously, make your broker sit down and go through each exclusion with real examples from your actual business. Don't just skim that section.
So worker's comp is pretty much required in most states anyway, but it's actually a solid deal. Your employees get their medical bills covered plus lost wages if they're injured - doesn't matter whose fault it was. On your end, you're protected from lawsuits, which honestly could destroy a small business overnight. Plus your team sees you've got their back, so they stick around longer. Just double-check your coverage matches your actual payroll and job types. I learned that one the hard way when my cousin got audited last year.
Honestly, start with checking their financial ratings on A.M. Best - you don't want them going under when you actually need to file a claim. Make sure they cover your industry's specific risks and can grow with your business. The claims process is where things get real though. I'd definitely ask other business owners about their actual experiences, not just read online reviews. Oh, and talk to reps from at least three companies before deciding. Cheapest isn't always best - you'll regret it if they're impossible to reach when something goes wrong.
Yeah, bundling usually saves decent money - like 10-25% compared to separate policies. Way easier dealing with one carrier instead of three different companies calling you about renewals and stuff. The coverage works better together too, so you won't have weird gaps between your liability and property insurance. Oh and the underwriting goes faster since they see your whole business at once instead of piecemeal. Honestly though, just get quotes both ways because every situation's different. Sometimes the savings aren't as good as they make it sound.
So here's the deal with tech and insurance - it hits you in two spots: coverage and cost. Your regular business insurance probably won't cover cyber stuff, which honestly is annoying but makes sense I guess. You'll need separate cyber coverage if you store customer info or run everything digitally. Insurance companies are also really nosy now about your security setup. They want to know about employee training, backups, all that stuff. Better security = cheaper rates though. I'd start with figuring out what data you actually collect and where you're vulnerable. That way you're not buying coverage you don't need.
Take photos of everything and save every single receipt - trust me on this one. Insurance companies are obsessed with documentation so give them what they want. Don't just wait around for your adjuster to call you either, bug them regularly. Oh and read through your actual policy beforehand, not when disaster strikes because that's honestly the worst timing ever. When they make their first offer? Don't take it. They're basically testing you and expect you'll negotiate. Most people don't realize they lowball on purpose.
Your location basically determines everything insurance-wise. Hurricane area? You'll need rock-solid property coverage plus business interruption. Earthquakes are the same headache, different disaster. Cities usually require higher liability limits - more people around means more lawsuits waiting to happen, honestly. Flooding's where people get screwed though, since regular policies don't cover it. I've seen businesses go under from that mistake. Rural spots sometimes get hit with weird workers' comp rates or can't even find certain coverage. Really depends on how far out you are. Start by figuring out what disasters could actually hit you, then work backwards from there.
Dude, you definitely need business auto insurance if you've got a fleet. Your regular business policy won't touch vehicle stuff - learned that the hard way from a friend's nightmare situation. Without fleet coverage, any accident becomes your personal problem, and we're talking potentially bankruptcy-level lawsuits here. Most states require it anyway, so you don't really have a choice. Look for liability, collision, comprehensive - the usual suspects. Oh, and medical payments coverage is smart too. Skip the big general insurers though. Go with companies that actually specialize in fleets - they'll give you better rates and usually throw in some fleet management tools that are actually useful.
-
Good research work and creative work done on every template.
-
Enough space for editing and adding your own content.
-
Innovative and Colorful designs.
-
It saves your time and decrease your efforts in half.
-
Professional and unique presentations.