

Unternehmensbewertung Präsentationsfolien





Try Before you Buy Download Free Sample Product
 Impress Your
Audience
 100%
Editable
 Save Hours
of Time


Fertig-Company-Bewertungs-PowerPoint-Präsentationsfolien, um alle Gewinne und den Nettowert zu analysieren, die Ihr Unternehmen erwirtschaftet hat. Führen Sie eine gründliche Bewertung des Managements, der Kapitalstruktur, der zukünftigen Ertragsperspektiven und mehr eines Unternehmens mit Hilfe von professionell gestalteten Vorlagen für die Unternehmensbewertungs-PPT-Präsentation durch. Bestimmen Sie den aktuellen Wert eines Unternehmens und beurteilen Sie alle Aspekte eines Unternehmens. Dieses Deck umfasst mehrere Vorlagen für die Unternehmensbewertungs-PowerPoint-Präsentation wie Bewertungsmethodik, Bewertungsschritte, Methoden der Unternehmensbewertung, Bestimmung des freien Cashflows, Bewertungsergebnisse, Geschäftsüberprüfungsprozess, Methodik der strategischen Überprüfung und mehr. Integrieren Sie eine Präsentation zur Unternehmensbewertung, um den Verkaufspreis des Unternehmens zu schätzen. Verwenden Sie Methoden der Unternehmensbewertung in PowerPoint-Techniken zur Bewertung eines Unternehmensvermögens wie Kostenansatz, Aufbaukosten, Wiederbeschaffungskosten, Marktansatz, abgezinster Cashflow, Prognose zukünftiger Cashflows usw. Greifen Sie auf das vollständige PowerPoint-Deck zur Unternehmensbewertung für eine Geschäftsanalyse zu. Verwenden Sie ein paar scherzhaften Ausdrücke mit unseren Company Valuation Powerpoint Presentation Slides. Das hilft, etwas Humor einzubringen.
People who downloaded this PowerPoint presentation also viewed the following :
Inhalt dieser Powerpoint-Präsentation
Folie 1: Diese Folie führt in die Unternehmensbewertung ein. Nennen Sie Ihren Firmennamen und beginnen Sie.
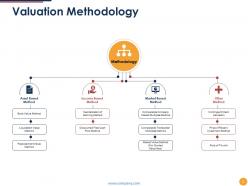
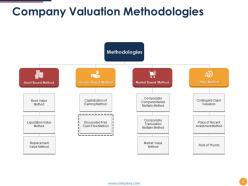
Folie 2: Auf dieser Folie wird die Bewertungsmethodik vorgestellt, die einige der Methoden in Form eines Flussdiagramms zeigt.
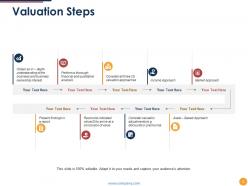
Folie 3: Auf dieser Folie werden die Bewertungsschritte mit einigen der folgenden Ansätze gezeigt: - Vermögensbasierter Ansatz - Abstimmung der angegebenen Werte, um zu einem Werturteil zu gelangen - Präsentation der Ergebnisse in einem Bericht - Berücksichtigung von Bewertungsanpassungen (z.B. Abschläge oder Prämien) - Ertragswertverfahren - Marktwertverfahren - Berücksichtigung aller drei (3) Bewertungsansätze - Eingehende Kenntnis des Unternehmens und der Unternehmensanteile - Gründliche finanzielle und qualitative Analyse
Folie 4: Auf dieser Folie werden die Methoden zur Unternehmensbewertung vorgestellt. Wir haben alle gängigen Bewertungsmethoden aufgelistet. Heben Sie die hervor, die Sie verwenden werden. Da DCF und relative Bewertung die am häufigsten verwendeten Methoden sind, haben wir sie in den späteren Folien ausführlicher besprochen.
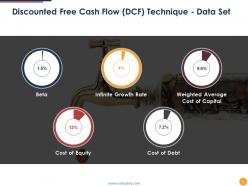
Folie 5: Diese Folie präsentiert die Discounted Free Cash Flow (DCF)-Technik - Datensatz. Sie können die Daten hinzufügen und nutzen.
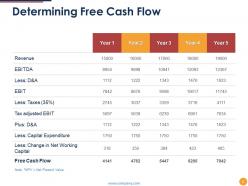
Folie 6: Auf dieser Folie wird die Ermittlung des freien Cashflows gezeigt. Fügen Sie die Daten hier ein und nutzen Sie sie.
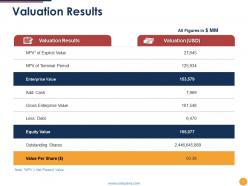
Folie 7: Diese Folie zeigt die Bewertungsergebnisse. Die folgende Methodik hilft bei der Bestimmung des Eigenkapitalwerts und des Aktienwerts des Unternehmens.
Folie 8: Auf dieser Folie wird die relative Bewertung mit Zusammenfassung und KGV mit Unternehmensdaten vorgestellt.
Folie 9: Diese Folie zeigt den Due-Diligence-Prozess für Unternehmen mit vier Schritten. Fügen Sie Ihre eigenen Informationen hinzu und nutzen Sie sie.
Folie 10: Auf dieser Folie wird die Methodik der strategischen Due Diligence vorgestellt. Sie können die Details hinzufügen und nutzen.
Folie 11: Diese Folie präsentiert die Unternehmensbewertungs-Symbolfolie.
Folie 12: Auf dieser Folie wird die Kaffeepause angekündigt.
Folie 13: Diese Folie zeigt den Titel Diagramme & Grafiken.
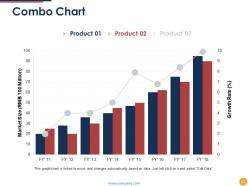
Folie 14: Auf dieser Folie wird ein Kombidiagramm vorgestellt. Damit können Sie Produkte vergleichen.
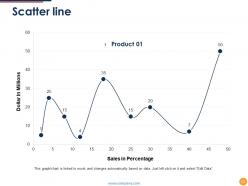
Folie 15: Diese Folie präsentiert ein Streuliniendiagramm. Fügen Sie die Daten ein und nutzen Sie es entsprechend.
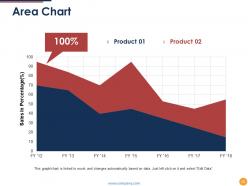
Folie 16: Flächendiagramm www.company.com 16 Produkt 01 Produkt 02 100% Dieses Diagramm ist mit Excel verknüpft und ändert sich automatisch basierend auf den Daten. Klicken Sie einfach mit der linken Maustaste darauf und wählen Sie "Daten bearbeiten".
Folie 17: Diese Folie trägt den Titel Zusätzliche Folien.
Folie 18: Auf dieser Folie wird Unsere Mission mit Textfeldern dargestellt.
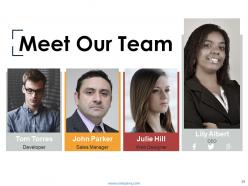
Folie 19: Auf dieser Folie wird Unser Team mit Namen und Bezeichnungen zum Ausfüllen vorgestellt.
Folie 20: Diese Folie hilft dabei, Über unser Unternehmen zu zeigen. Die Unterüberschriften lauten: Kreatives Design, Kundenbetreuung, Unternehmenserweiterung.
Folie 21: Auf dieser Folie werden die Ziele Ihres Unternehmens dargestellt.
Folie 22: Diese Folie zeigt einen Vergleich von positiven und negativen Faktoren mit Daumen-hoch- und Daumen-runter-Symbolen.
Folie 23: Dies ist eine Folie zur Finanzbewertung, um hier finanzielle Aspekte darzustellen.
Folie 24: Dies ist eine Zitatefolie, um Botschaften, Überzeugungen usw. zu vermitteln.
Folie 25: Auf dieser Folie wird ein Venn-Diagramm angezeigt.
Folie 26: Dies ist eine Dankesfolie mit Adresse, E-Mail und Kontaktnummer.
Unternehmensbewertung Powerpoint-Präsentationsfolien mit allen 26 Folien
Bestehen Sie darauf, sich bei unserer Präsentation zur Unternehmensbewertung ausschließlich auf Fakten zu konzentrieren. Zeigen Sie intellektuelle Integrität.
-
Company Valuation
-
Valuation Methodology
-
Valuation Steps
-
Company Valuation Methodologies
-
Discounted Free Cash Flow DCF Technique Data Set
-
Determining Free Cash Flow
-
Valuation Results
-
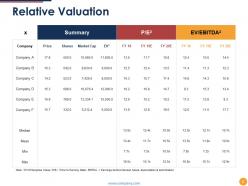
Relative Valuation
-
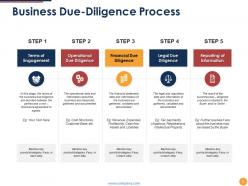
Business Due Diligence Process
-
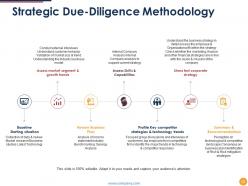
Strategic Due Diligence Methodology
-
Company Valuation Icon Slide
-
Coffee Break Time
-
Graphs And Charts
-
Combo Chart
-
Scatter line
-
Area Chart
-
Additional Slides
-
Our Mission
-
Meet Our Team
-
About Us
-
Our Goals
-
Comparison
-
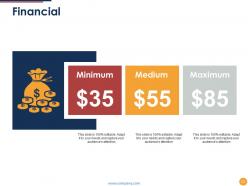
Financial
-
Company Valuation
-
Venn
-
Thank You
FAQs for Company Valuation
So there's basically three ways to value a company. Asset-based just looks at what they own minus debt - simple but usually lowballs growing businesses. Then there's income-based like DCF where you project future cash flows and discount them back (though honestly those projections are often total guesswork). Market-based compares to similar companies that sold recently or are public. Each works better for different industries and situations. Oh and definitely use at least two methods to get a decent range - don't just pick one and call it done.
Look, market vibes totally change what people will pay for companies. Bull markets? Everyone's throwing money around and P/E ratios go crazy high. Bear markets flip that script - suddenly nobody cares about your "growth story" if it's overpriced. Interest rates mess with your DCF models too since they change discount rates. Honestly, I learned this the hard way last year. The trick is comparing to recent deals, not some old benchmarks from 2019. Current market sentiment matters way more than historical averages when you're actually trying to price something.
Look, financial statements are your starting point for any valuation - they've got all the raw data you need. Pull revenue, margins, cash flow, and debt straight from the income statement, balance sheet, and cash flow statement. That's what feeds your models. But here's the thing - you can't value a company with garbage data. It's like trying to bake without knowing what's actually in your ingredients. Quality of your valuation depends entirely on solid financials. Always check the footnotes too. Companies love hiding weird accounting stuff in there that'll mess up your numbers if you're not careful.
Honestly, there are a few ways to tackle this. Most people go with the income approach - figure out what cash flows the brand will generate, then discount back to today's value. Market approach is another option where you compare to similar brand sales, but finding good matches is basically impossible. Cost approach just adds up what it'd take to build the brand from zero. My take? Don't overthink getting one perfect number. Use two or three methods and see where they land you - that range is probably more realistic anyway than pretending you can nail it exactly.
So EBITDA strips away all the financial engineering stuff - taxes, interest payments, depreciation - and shows you what the business actually makes from operations. Investors love it because they can plug in their own financing structure later. Makes sense, right? It's also clutch for comparing companies that might have totally different debt loads or tax situations. Like, you can finally see apples to apples. Just don't completely ignore those "removed" costs though - interest and taxes are still real money going out the door that whoever buys will have to deal with.
So you'd bake future growth into your DCF by bumping up those revenue projections and terminal value rates. If you think the company's gonna crush it compared to competitors, forecast higher cash flows in the later years. The hard part? Being realistic about it - I've seen way too many people convince themselves they're valuing the next Amazon when it's really just another decent business. You need actual reasons for those growth assumptions though, like solid expansion plans or new products in the pipeline. Definitely run conservative, base case, and optimistic scenarios to see how much your valuation swings.
So industry comps are basically your sanity check - you look at what similar companies are trading for and use those multiples (P/E, EV/EBITDA, revenue multiples) to value your target. Pretty straightforward stuff. Finding truly comparable companies though? That's where it gets annoying. You need similar size, growth, margins - the whole package. I usually grab like 5-10 solid comps and see where my company lands in that range. Just don't get lazy with the selection process or you'll end up comparing a tech startup to IBM or something equally useless.
So basically, when interest rates go up, it makes future cash flows worth less today - which absolutely murders growth stocks since they're all about future potential. Inflation's weird though. Sure, companies might get higher revenues, but their costs spike too. Higher rates also make bonds look way more appealing than stocks, so money flows out of equities. Different sectors get hit differently, which is honestly kind of annoying to track. My advice? Look for companies that can actually raise their prices when inflation hits, and ones with solid cash flow right now. And yeah, you'll want to recalculate your valuations when rates move big.
Don't get stuck using old comps or fall in love with just one valuation method. I've watched so many deals blow up because people assumed crazy growth rates like 30% forever - totally unrealistic. Management quality matters way more than people think, even if the financials look amazing. Market conditions can mess everything up too. You want to run DCF, comp analysis, and precedent transactions, then see where they all land. Never put all your eggs in one basket with these things. Oh, and seriously avoid those overly optimistic projections - they'll bite you every time.
Honestly, company size totally changes how you value businesses. Big public companies? You've got tons of data, so comparable analysis and DCF models work great. But small businesses are a nightmare - their books are usually messy, so you end up using asset-based methods or whatever industry multiples you can find. Private companies fall somewhere between the two. The trick is just matching your approach to whatever decent data you can actually get your hands on. Don't overthink it with some complex model when the numbers aren't even reliable to begin with.
DCF calculates what your company's actually worth by projecting future cash flows and bringing them back to today's value. Pretty straightforward math, honestly. CCA works differently - you're comparing your business to similar public companies already trading. It's like selling your house. DCF would be figuring out construction costs and rental potential. CCA? Just seeing what comparable houses sold for in your area recently. Oh, and definitely run both methods. They'll give you a solid range and one usually backs up the other.
So basically you bump up your discount rate when there's more risk involved - riskier companies need to offer higher returns to attract investors, which drives down the present value. In DCF models, I usually increase the WACC based on stuff like market volatility or regulatory headaches. Beta calculations are honestly such a headache but they do help quantify this. Oh and definitely run some scenarios with different risk assumptions - like what happens if things go south? Document the risks you can't put numbers on. The key is running sensitivity analyses so you can see how different risk levels mess with your valuation range.
So ownership structure totally changes how much a company's worth. Majority stakes get like 20-30% premiums because you actually control stuff - makes sense, right? But minority positions? They usually take 10-25% haircuts since you're basically just along for the ride. Public companies trade higher than private ones mostly due to liquidity. Family businesses are weird though - sometimes they get discounted for sketchy governance, other times they're worth more because they're stable. I've seen it go both ways honestly. Just make sure you're thinking about who owns what when you're running numbers.
Honestly, I'd do it at least once a year, but it really comes down to where you're at. If you're early stage? Maybe quarterly since everything's moving so fast. More established companies can probably get away with annual check-ins. But here's the thing - don't just stick to a schedule. Big product launch, fundraising round, or your industry gets shaken up? Time for a fresh look. I actually missed doing this once and it bit me during negotiations. Set a reminder right now or you'll totally forget. Trust me on that one.
You'd use liquidation value when a company's basically circling the drain - bankruptcy, might shut down, that kind of mess. Manufacturing companies are perfect examples. If they're struggling, you don't care about ongoing operations anymore. What matters is what those machines would sell for at auction, you know? Asset-heavy businesses make sense for this too. Insurance companies love liquidation values for obvious reasons. Honestly, any time you're worried about downside risk or the business won't survive, that's when you'd calculate it instead of fair market value.
-
Enough space for editing and adding your own content.
-
Amazing product with appealing content and design.