

Finanzierung von Immobilienprojekten Powerpoint-Präsentationsfolien




Try Before you Buy Download Free Sample Product
 Impress Your
Audience
 100%
Editable
 Save Hours
of Time


Die Immobilienbranche gilt als einer der entscheidenden Faktoren für eine Wirtschaft. Man kann leicht einen stetigen Cashflow haben oder große Renditen erzielen, indem man in Immobilien investiert. Schauen Sie sich unsere effizient gestaltete Präsentation zur Finanzierung von Immobilienprojekten an. Diese Vorlage hilft den Immobilienentwicklern bei der Ermittlung der besten Finanzierungsquelle, die ihnen hilft, die Finanzierungsanforderungen zu erfüllen. Die Präsentation beginnt mit der Marktübersicht und den Abschnitten zur Leistung unserer Wettbewerber, die das Unternehmen verwenden kann, um wichtige Statistiken, Treiber, Akteure der Immobilienbranche und eine unternehmensspezifische Wettbewerbslandschaft zu veranschaulichen. Abschnitte wie das Immobilienprojekt, der Projektdurchführbarkeitsbericht und die Identifizierung und Erfüllung der Projektfinanzierungsanforderungen helfen den Entwicklern, detaillierte Details über das Projekt hervorzuheben, die Projektdurchführbarkeit zu prüfen und die beste Projektfinanzierungsstruktur zu bestimmen und auszuwählen. Entwickler können Folien verwenden, nämlich Immobilienprojektfinanzierung und -implementierung, und Abschnitte wie das Verwalten von Projektrisiken und das Projektmanagementteam, um eine effektive Projektentwicklung, -finanzierung und -verwaltung sicherzustellen. Schließlich werden Projektmanagement-Dashboards Immobilienunternehmen dabei unterstützen, ihren Projektfortschritt und ihre Teamleistung zu bestimmen. Packen Sie dieses PPT-Layout jetzt für ein problemloses Erlebnis ein.
People who downloaded this PowerPoint presentation also viewed the following :
Inhalt dieser Powerpoint-Präsentation
Folie 1 : Diese Folie stellt die Finanzierung von Immobilienprojekten vor. Geben Sie Ihren Firmennamen an und beginnen Sie.
Folie 2 : Diese Folie gibt die Agenda der Präsentation an.
Folie 3 : Diese Folie zeigt das Inhaltsverzeichnis für die Präsentation.
Folie 4 : Diese Folie hebt Titel für Themen hervor, die als nächstes in der Vorlage behandelt werden sollen.
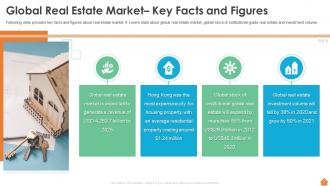
Folie 5 : Diese Folie zeigt wichtige Fakten und Zahlen zum Immobilienmarkt.
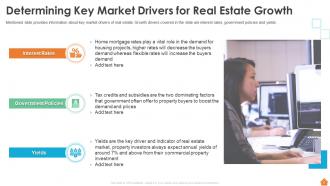
Folie 6 : Diese Folie zeigt die Bestimmung der wichtigsten Markttreiber für das Immobilienwachstum.
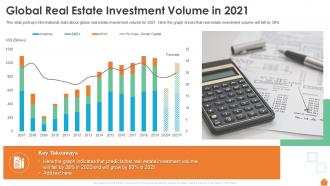
Folie 7 : Diese Folie zeigt das globale Immobilieninvestitionsvolumen im Jahr 2021.
Folie 8 : Diese Folie zeigt Informationen über führende Immobilienanbieter auf dem US-Markt.
Folie 9 : Diese Folie hebt Titel für Themen hervor, die als nächstes in der Vorlage behandelt werden sollen.
Folie 10 : Diese Folie zeigt die unternehmensspezifische Wettbewerbslandschaft.
Folie 11 : Diese Folie zeigt den Marktanteil unserer Konkurrenten im Inland.
Folie 12 : Diese Folie hebt Titel für Themen hervor, die als nächstes in der Vorlage behandelt werden sollen.
Folie 13 : Diese Folie stellt die Ziele und den Umfang des Projektkontexts dar.
Folie 14 : Die erwähnte Folie veranschaulicht rechtliche Informationen über den Projektstandort.
Folie 15 : Diese Folie enthält Informationen über den Standort des Projekts und sein Design-Layout.
Folie 16 : Die folgende Folie zeigt den Entwicklungszyklus des Immobilienprojekts des Unternehmens.
Folie 17 : Diese Folie zeigt die Definition unseres vierstufigen Projektentwicklungsprozesses.
Folie 18 : Diese Folie hebt Titel für Themen hervor, die als nächstes in der Vorlage behandelt werden sollen.
Folie 19 : Diese Folie präsentiert fünfjährige Rentabilitätsprognosen des Projekts.
Folie 20 : Diese Folie zeigt Finanzkennzahlen, die die Projektdurchführbarkeit definieren.
Folie 21 : Diese Folie stellt die für den Projektabschluss erforderlichen Ressourcen dar.
Folie 22 : Diese Folie zeigt die leistungsbasierte Anbieterklassifizierung und -auswahl.
Folie 23 : Diese Folie hebt Titel für Themen hervor, die als nächstes in der Vorlage behandelt werden sollen.
Folie 24 : Diese Folie zeigt verfügbare Finanzierungsquellen für Immobilien.
Folie 25 : Diese Folie präsentiert Arten von Finanzierungsstrukturen für das Projekt.
Folie 26 : Diese Folie zeigt Informationen über die Struktur der Immobilienprojektfinanzierung des Unternehmens.
Folie 27 : Dies ist eine weitere Folie, die die Immobilienprojektfinanzierungsstruktur des Unternehmens fortführt.
Folie 28 : Diese Folie hebt Titel für Themen hervor, die als nächstes in der Vorlage behandelt werden sollen.
Folie 29 : Diese Folie zeigt Einzelheiten über den Entwicklungszeitplan für die Finanzierung von Immobilienprojekten.
Folie 30 : Diese Folie zeigt den Zeitplan für die Implementierung von Immobilienprojekten.
Folie 31 : Diese Folie hebt Titel für Themen hervor, die als nächstes in der Vorlage behandelt werden sollen.
Folie 32 : Diese Folie zeigt die Struktur des Projektrisikos, die in vier Bereiche unterteilt ist.
Folie 33 : Diese Folie zeigt die Bestimmung des Risikoniveaus im gesamten Immobilienentwicklungsprozess.
Folie 34 : Diese Folie zeigt die Risikoauswirkungs- und Wahrscheinlichkeitsbewertung des Projekts.
Folie 35 : Diese Folie zeigt den Minderungsplan zur Überwindung von Projektrisiken.
Folie 36 : Diese Folie hebt Titel für Themen hervor, die als nächstes in der Vorlage behandelt werden sollen.
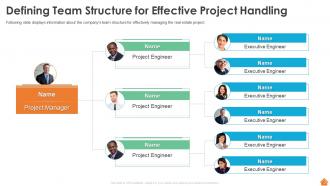
Folie 37 : Diese Folie zeigt die Definition der Teamstruktur für eine effektive Projektabwicklung.
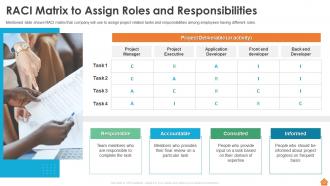
Folie 38 : Diese Folie zeigt die RACI-Matrix zum Zuweisen von Rollen und Verantwortlichkeiten.
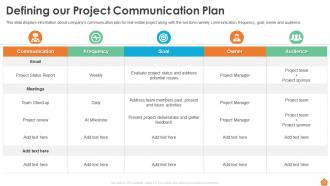
Folie 39 : Diese Folie enthält Informationen über den Kommunikationsplan des Unternehmens für Immobilienprojekte.
Folie 40 : Diese Folie hebt Titel für Themen hervor, die als nächstes in der Vorlage behandelt werden sollen.
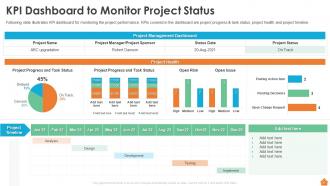
Folie 41 : Diese Folie zeigt das KPI-Dashboard zur Überwachung des Projektstatus.
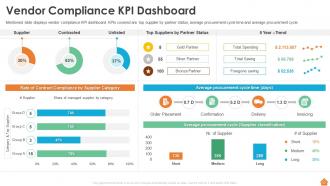
Folie 42 : Diese Folie zeigt das Vendor Compliance KPI Dashboard.
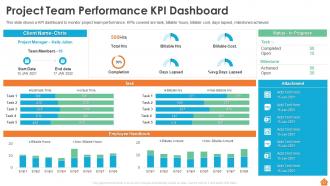
Folie 43 : Diese Folie zeigt das KPI-Dashboard für die Projektteamleistung.
Folie 44 : Diese Folie zeigt Symbole für die Finanzierung von Immobilienprojekten.
Folie 45 : Diese Folie trägt den Titel „Zusätzliche Folien“, um voranzukommen.
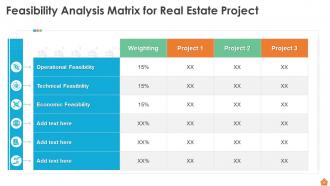
Folie 46 : Diese Folie stellt die Machbarkeitsanalysematrix für Immobilienprojekte dar.
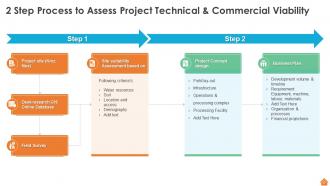
Folie 47 : Diese Folie zeigt den zweistufigen Prozess zur Bewertung der technischen und kommerziellen Realisierbarkeit des Projekts.
Folie 48 : Dies ist die Folie „Über uns“, um Unternehmensspezifikationen usw. anzuzeigen.
Folie 49 : Dies ist die Folie „Unser Team“ mit Namen und Bezeichnung.
Folie 50 : Dies ist unsere Missionsfolie mit zugehörigen Bildern und Texten.
Folie 51 : Dies ist unsere Zielfolie. Geben Sie hier Ihre Ziele an.
Folie 52 : Diese Folie präsentiert die Roadmap mit zusätzlichen Textfeldern.
Folie 53 : Diese Folie enthält ein Puzzle mit zugehörigen Symbolen und Text.
Folie 54 : Dies ist eine Finanzfolie. Zeigen Sie hier Ihre finanzbezogenen Sachen.
Folie 55 : Diese Folie zeigt Mind Map mit verwandten Bildern.
Folie 56 : Diese Folie zeigt ein Venn-Diagramm mit Textfeldern.
Folie 57 : Diese Folie zeigt Trichter mit zugehörigen Symbolen und Text.
Folie 58 : Dies ist eine Timeline-Folie. Zeigen Sie hier Daten zu Zeitintervallen an.
Folie 59 : Dies ist eine Dankeschön-Folie mit Adresse, Kontaktnummern und E-Mail-Adresse.
Finanzierung von Immobilienprojekten PowerPoint-Präsentationsfolien mit allen 64 Folien:
Verwenden Sie unsere Powerpoint-Präsentationsfolien zur Finanzierung von Immobilienprojekten, um Ihnen effektiv dabei zu helfen, wertvolle Zeit zu sparen. Sie sind gebrauchsfertig und passen in jede Präsentationsstruktur.
-
Financing of Real Estate Project
-
Agenda for Financing of Real Estate Project
-
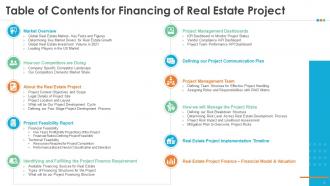
Table of Contents for Financing of Real Estate Project
-
Market Overview
-
Global Real Estate Market Key Facts and Figures
-
Determining Key Market Drivers for Real Estate Growth
-
Global Real Estate Investment Volume in 2021
-
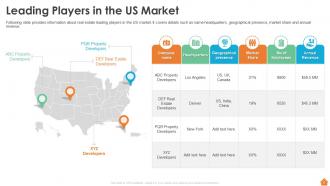
Leading Players in the US Market
-
How our Competitors are Doing
-
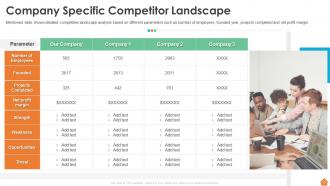
Company Specific Competitor Landscape
-
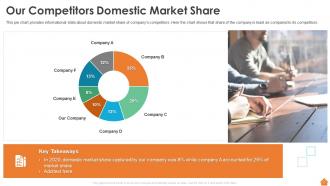
Our Competitors Domestic Market Share
-
About the Real Estate Project
-
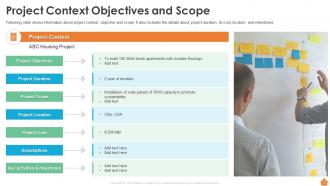
Project Context Objectives and Scope
-
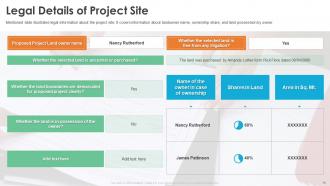
Legal Details of Project Site
-
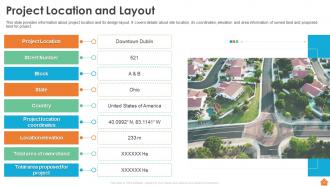
Project Location and Layout
-
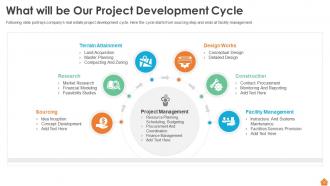
What will be Our Project Development Cycle
-
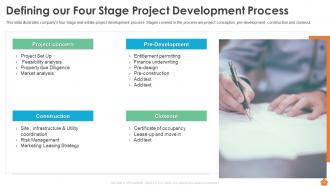
Defining our Four Stage Project Development Process
-
Project Feasibility Report
-
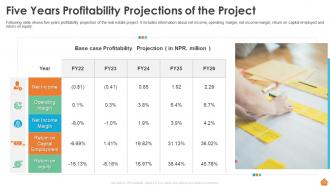
Five Years Profitability Projections of the Project
-
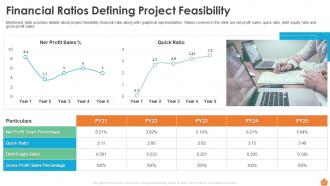
Financial Ratios Defining Project Feasibility
-
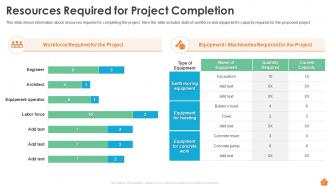
Resources Required for Project Completion
-
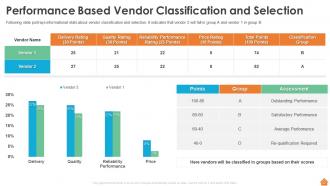
Performance Based Vendor Classification and Selection
-
Identifying and Fulfilling the Project Finance Requirement
-
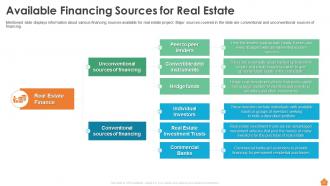
Available Financing Sources for Real Estate
-
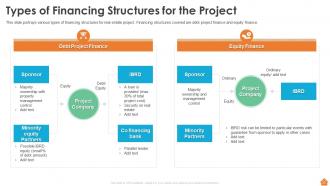
Types of Financing Structures for the Project
-
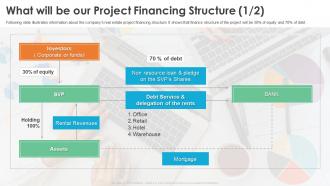
What will be our Project Financing Structure 1 2
-
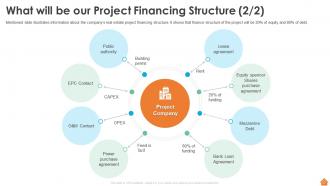
What will be our Project Financing Structure 2 2
-
Real Estate Project Finance Financial Model Valuation Real Estate Project Implementation Timeline
-
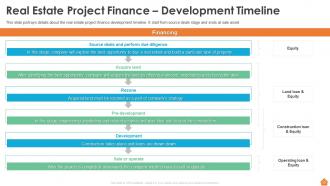
Real Estate Project Finance Development Timeline
-
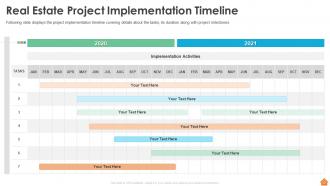
Real Estate Project Implementation Timeline
-
How we will Manage the Project Risks
-
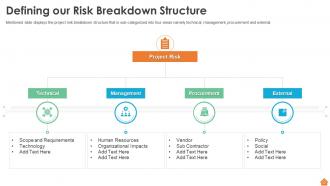
Defining our Risk Breakdown Structure
-
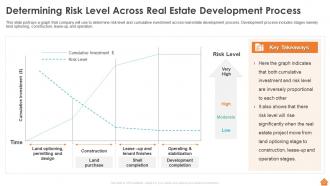
Determining Risk Level Across Real Estate Development Process
-
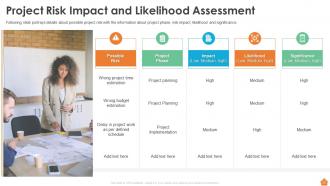
Project Risk Impact and Likelihood Assessment
-
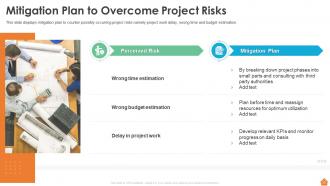
Mitigation Plan to Overcome Project Risks
-
Project Management Team
-
Defining Team Structure for Effective Project Handling
-
RACI Matrix to Assign Roles and Responsibilities
-
Defining our Project Communication Plan
-
Project Management Dashboards
-
KPI Dashboard to Monitor Project Status
-
Vendor Compliance KPI Dashboard
-
Project Team Performance KPI Dashboard
-
Icon Slide for Financing of Real Estate Project
-
Additional Slides
-
Feasibility Analysis Matrix for Real Estate Project
-
Financing of Real Estate Project
-
About Us
-
Meet Our Team
-
Our Mission
-
Our Target
-
Roadmap
-
Puzzle
-
Financial
-
Mind Map
-
Venn
-
Hiring Funnel Sourcing Screening Assessing Verifying
-
Timeline
-
Thank You
-

-

-

-

-

FAQs for Financing Of Real Estate Project
Interest rates are obviously key - fixed vs adjustable makes a big difference. Down payment size will hit your monthly payments hard, plus you might get stuck with PMI if it's too low. 15-year vs 30-year loans? The monthly payments jump but you save tons long-term (honestly wish I'd known this earlier). Credit score basically determines what doors even open for you. Closing costs can be brutal - like way more than you'd expect. Check the lender's rep too and how fast they actually close. I'd get pre-approved with 2-3 different places so you can compare real numbers.
Hey! So rates mess with your returns in two big ways. Your mortgage payments get more expensive, which obviously cuts into your monthly cash flow. Property values usually drop too since fewer people can actually afford to buy anything. Honestly, it's kind of brutal when rates spike fast like they did recently. But when rates are low? You can borrow more money and property prices tend to go up. My advice - try to time your purchases when rates aren't terrible, and always run the numbers assuming they'll jump another 2-3% just to be safe.
So fixed-rate means your payment stays exactly the same every month - super nice for budgeting. Variable rates start cheaper, which is tempting, but they bounce around with the market. Honestly feels like rolling dice sometimes. You're basically choosing between playing it safe or gambling that rates won't spike. If you're planning to move in a few years anyway, variable might be worth the risk. But if you're the type who loses sleep over money stuff (no judgment - I totally get it), fixed gives you that peace of mind. Really comes down to your situation.
So basically, you put down way less cash but control way more property. Like instead of buying one $200k house outright, you could do 20% down on five houses - now you're making money off $1M in real estate instead of just $200k. Pretty sweet when prices go up, right? But here's the thing - if the market tanks or you can't make payments, you're screwed on a much bigger scale. Honestly though, I'd just start with one property first. Get used to dealing with tenants and maintenance before you go crazy with it.
Look, your credit score is basically everything when it comes to getting good loan terms. Above 740? Lenders will actually fight for you with their best rates. Below that and you're paying more - sometimes way more. I'm talking thousands extra over the loan life, which is honestly insane when you think about it. Even 20 points can make a huge difference. Got time before you need the loan? Pay down those credit cards first and check your report for errors. Trust me, it's worth the wait if your score needs work.
So you've got a few routes here. Conventional loans need like 20-25% down for investment properties - pretty standard stuff. Hard money's insanely expensive but if you need to close fast, it works. There's also DSCR loans which are kinda cool because they look at the property's cash flow instead of your income. Portfolio loans from local banks are worth checking out since they don't sell them off to other lenders. Oh and commercial loans if you're going bigger. Honestly though? I'd hit up some local portfolio lenders first - they're way more flexible than the big guys.
So REITs can actually raise money way easier than if you bought property directly. They issue stocks, sell corporate bonds, get credit lines that we regular people can't access. Pretty unfair honestly. But here's the thing - they have to pay out 90% of their profits as dividends, which is great for us but means they're always hunting for outside money to grow. You'd just use mortgages and whatever cash you have. REITs cost more to finance but you get way better liquidity and don't have all your eggs in one building.
So hard money lenders are basically when you need cash fast but don't mind paying through the nose for it. Think 10-15% interest plus fees - pretty brutal honestly. The upside? Funding happens in days, not weeks, and they care more about the property than your credit score. Perfect for flippers who spot a good deal and can't wait around. Just know you're looking at 6-12 month terms max, so you better flip that house quick or have another way out. I'd only use them when time is everything and the numbers still work after those crazy rates.
Oh man, commercial down payments are rough. You'll need 20-35% minimum, which is crazy compared to residential where you can sometimes get away with just 3-5%. Banks think commercial stuff is way riskier so they want more cash upfront. Your credit matters too, obviously. Some lenders are pickier than others depending on what type of property you're buying. I learned this the hard way when I was looking into it last year - definitely start saving now if you're serious about it because closing day hits different when you need that much cash.
Hey! So you're gonna need a bunch of stuff - recent pay stubs, your last two years of W-2s or tax returns, and bank statements. Also employment verification letters. Credit card statements and any existing loan info too since they want to see your whole financial picture. Once you're under contract, you'll need the purchase agreement and property appraisal. Honestly, start gathering everything now because it's such a pain tracking down old documents - I learned that the hard way. My bank took forever to get me statements from like 18 months ago.
So basically these crowdfunding sites let you pool money with other people to buy real estate you'd never afford alone. You can start with like $500-$1000 instead of needing hundreds of thousands upfront. Pretty crazy that you can invest in some Miami property while sitting in Denver, right? Plus smaller developers don't have to deal with banks taking forever to approve stuff. I'd honestly just check out Fundrise or RealtyMogul first - they'll show you exactly how it works and you can poke around before committing to anything.
Okay so high-leverage financing is basically borrowing a ton of money to buy property - amplifies your gains but also your losses big time. Cash flow becomes your enemy when vacancy rates jump or interest rates go up. You've got way less equity as a safety net, so even small drops in property values can put you underwater on the loan. Trust me, the math gets brutal when you're at 90%+ leverage and suddenly need to cover major repairs or deal with empty units for months. Honestly I'd run some nightmare scenarios first - like what happens if half your units go empty? See if you can actually survive that before diving in.
Residential stuff is super standardized - you know, 30-year mortgages, FHA loans, basic credit checks. Commercial? Total chaos honestly. Banks care way more about the property's income potential and whether you actually know what you're doing. Down payments are bigger, rates suck more, and terms are shorter like 5-10 years. Oh and forget doing it online - you'll need to schmooze with local bankers first. For residential you can just get pre-qualified online no problem, but commercial is all about relationships.
Dude, lenders are getting super creative right now. ARMs are back because fixed rates still suck. Bridge loans and rent-to-own stuff is everywhere too - honestly didn't see that coming a few years ago. Banks tightened up so private lenders are filling the gap, which is actually pretty smart if you can find good ones. Everything's going digital now - closings, AI doing the underwriting, all that. My advice? Don't just stick with traditional banks. Build some relationships with private guys as your backup plan. You'll need options in this market.
Here's what I'd do - grab a spreadsheet and run both scenarios side by side. For the financed option, take your annual cash flow after paying the mortgage and divide that by whatever cash you put down initially. That's your return rate. Then compare it to just buying all-cash (boring but simple, right?). Don't forget about loan fees and interest costs - they add up quick. If your financed return beats what you could make elsewhere by a solid margin, then financing probably makes sense. I mean, cash does feel way safer though.
-
Thank you for offering such helpful pre-designed templates. They are really beneficial to me in my job.
-
Their professional templates are very impressive, even my manager was curious about the source. I am very grateful.