

Financiamiento del proyecto inmobiliario Diapositivas de presentación de Powerpoint




Try Before you Buy Download Free Sample Product
 Impress Your
Audience
 100%
Editable
 Save Hours
of Time


La industria de bienes raíces se considera uno de los contribuyentes críticos para una economía. Uno puede tener fácilmente un flujo de efectivo constante o puede obtener grandes ganancias invirtiendo en bienes raíces. Vea nuestra presentación diseñada de manera eficiente sobre Financiamiento de Proyectos Inmobiliarios. Esta plantilla ayudará a los promotores inmobiliarios a identificar la mejor fuente de financiación que les ayudará a cumplir con los requisitos de financiación. La presentación comienza con la descripción general del mercado y cómo nuestros competidores están haciendo secciones que la organización puede usar para ilustrar las principales estadísticas, impulsores, actores de la industria de bienes raíces y un panorama de competencia específico de la empresa. Secciones como sobre el proyecto inmobiliario, el informe de viabilidad del proyecto y la identificación y el cumplimiento de los requisitos de financiación del proyecto ayudarán a los desarrolladores a resaltar detalles detallados sobre el proyecto, verificar la viabilidad del proyecto y determinar y seleccionar la mejor estructura de financiación del proyecto. Los desarrolladores pueden usar diapositivas, a saber, financiación e implementación de proyectos inmobiliarios, y secciones como gestión de riesgos de proyectos y equipo de gestión de proyectos para garantizar un desarrollo, financiación y gestión de proyectos efectivos. Por último, los paneles de gestión de proyectos ayudarán a las empresas inmobiliarias a determinar el progreso de sus proyectos y el rendimiento del equipo. Para una experiencia sin complicaciones, empaquete este diseño PPT ahora mismo.
People who downloaded this PowerPoint presentation also viewed the following :
Contenido de esta presentación de Powerpoint
Diapositiva 1 : Esta diapositiva presenta el Financiamiento de Proyectos Inmobiliarios. Indique el nombre de su empresa y comience.
Diapositiva 2 : Esta diapositiva indica la Agenda de la presentación.
Diapositiva 3 : Esta diapositiva presenta la tabla de contenido de la presentación.
Diapositiva 4 : esta diapositiva resalta el título de los temas que se cubrirán a continuación en la plantilla.
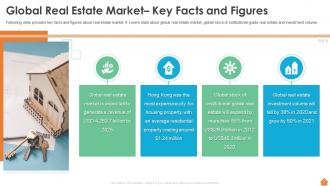
Diapositiva 5 : Esta diapositiva muestra datos y cifras clave sobre el mercado inmobiliario.
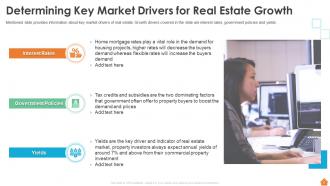
Diapositiva 6 : esta diapositiva representa la determinación de los impulsores clave del mercado para el crecimiento inmobiliario.
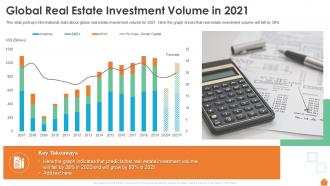
Diapositiva 7 : Esta diapositiva muestra el volumen de inversión inmobiliaria global en 2021.
Diapositiva 8 : Esta diapositiva muestra información sobre los principales actores inmobiliarios en el mercado estadounidense.
Diapositiva 9 : esta diapositiva resalta el título de los temas que se cubrirán a continuación en la plantilla.
Diapositiva 10 : Esta diapositiva presenta el panorama de la competencia específica de la empresa.
Diapositiva 11 : Esta diapositiva muestra la participación de mercado nacional de nuestros competidores.
Diapositiva 12 : esta diapositiva resalta el título de los temas que se cubrirán a continuación en la plantilla.
Diapositiva 13 : esta diapositiva representa los objetivos y el alcance del contexto del proyecto.
Diapositiva 14 : La diapositiva mencionada ilustra información legal sobre el sitio del proyecto.
Diapositiva 15 : esta diapositiva proporciona información sobre la ubicación del proyecto y su diseño.
Diapositiva 16 : La siguiente diapositiva muestra el ciclo de desarrollo del proyecto inmobiliario de la empresa.
Diapositiva 17 : Esta diapositiva muestra la definición de nuestro proceso de desarrollo de proyectos de cuatro etapas.
Diapositiva 18 : esta diapositiva destaca el título de los temas que se cubrirán a continuación en la plantilla.
Diapositiva 19 : Esta diapositiva presenta Proyecciones de rentabilidad del proyecto a cinco años.
Diapositiva 20 : Esta diapositiva muestra las razones financieras que definen la viabilidad del proyecto.
Diapositiva 21 : Esta diapositiva representa los recursos necesarios para la finalización del proyecto.
Diapositiva 22 : Esta diapositiva muestra la clasificación y selección de proveedores basada en el desempeño.
Diapositiva 23 : esta diapositiva destaca el título de los temas que se cubrirán a continuación en la plantilla.
Diapositiva 24 : Esta diapositiva muestra las Fuentes de Financiamiento Disponibles para Bienes Raíces.
Diapositiva 25 : Esta diapositiva presenta los tipos de estructuras de financiamiento para el proyecto.
Diapositiva 26 : Esta diapositiva muestra información sobre la estructura de financiamiento de proyectos inmobiliarios de la empresa.
Diapositiva 27 : Esta es otra diapositiva que continúa con la estructura de financiamiento de proyectos inmobiliarios de la empresa.
Diapositiva 28 : esta diapositiva resalta el título de los temas que se cubrirán a continuación en la plantilla.
Diapositiva 29 : Esta diapositiva muestra detalles sobre el cronograma de desarrollo de la financiación de proyectos inmobiliarios.
Diapositiva 30 : esta diapositiva presenta el cronograma de implementación del proyecto inmobiliario.
Diapositiva 31 : esta diapositiva destaca el título de los temas que se cubrirán a continuación en la plantilla.
Diapositiva 32 : esta diapositiva muestra la estructura de desglose del riesgo del proyecto que se subcategoriza en cuatro áreas.
Diapositiva 33 : Esta diapositiva representa la determinación del nivel de riesgo en el proceso de desarrollo inmobiliario.
Diapositiva 34 : esta diapositiva muestra la evaluación del impacto y la probabilidad del riesgo del proyecto.
Diapositiva 35 : Esta diapositiva muestra el plan de mitigación para superar los riesgos del proyecto.
Diapositiva 36 : esta diapositiva resalta el título de los temas que se cubrirán a continuación en la plantilla.
Diapositiva 37 : Esta diapositiva presenta la definición de la estructura del equipo para un manejo efectivo del proyecto.
Diapositiva 38 : Esta diapositiva muestra la matriz RACI para asignar roles y responsabilidades.
Diapositiva 39 : Esta diapositiva representa información sobre el plan de comunicación de la empresa para el proyecto inmobiliario.
Diapositiva 40 : esta diapositiva destaca el título de los temas que se cubrirán a continuación en la plantilla.
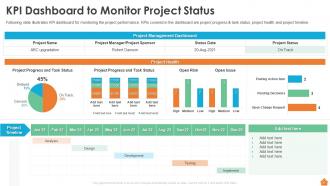
Diapositiva 41 : Esta diapositiva muestra el Panel de KPI para monitorear el estado del proyecto.
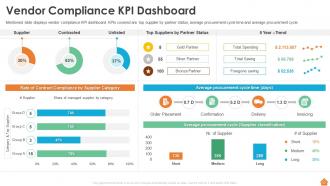
Diapositiva 42 : esta diapositiva muestra el panel de KPI de cumplimiento del proveedor.
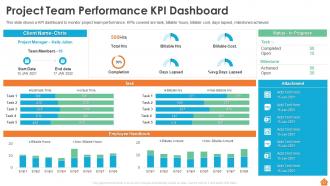
Diapositiva 43 : Esta diapositiva presenta el Panel de KPI de rendimiento del equipo del proyecto.
Diapositiva 44 : esta diapositiva muestra iconos para la financiación de proyectos inmobiliarios.
Diapositiva 45 : esta diapositiva se titula Diapositivas adicionales para avanzar.
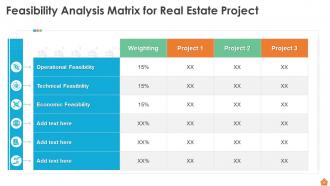
Diapositiva 46 : Esta diapositiva representa la matriz de análisis de factibilidad para un proyecto inmobiliario.
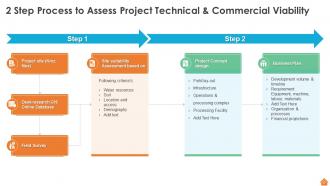
Diapositiva 47 : Esta diapositiva muestra el proceso de 2 pasos para evaluar la viabilidad técnica y comercial del proyecto.
Diapositiva 48 : Esta es la diapositiva Acerca de nosotros para mostrar las especificaciones de la empresa, etc.
Diapositiva 49 : Esta es la diapositiva Nuestro equipo con nombres y designación.
Diapositiva 50 : Esta es la diapositiva Nuestra misión con imágenes y texto relacionados.
Diapositiva 51 : Esta es la diapositiva Nuestro objetivo. Indique sus objetivos aquí.
Diapositiva 52 : esta diapositiva presenta la hoja de ruta con cuadros de texto adicionales.
Diapositiva 53 : Esta diapositiva contiene Rompecabezas con íconos y texto relacionados.
Diapositiva 54 : Esta es una diapositiva financiera. Muestre sus cosas relacionadas con las finanzas aquí.
Diapositiva 55 : esta diapositiva muestra el mapa mental con imágenes relacionadas.
Diapositiva 56 : Esta diapositiva muestra el diagrama de Venn con cuadros de texto.
Diapositiva 57 : Esta diapositiva muestra Funnel con íconos y texto relacionados.
Diapositiva 58 : Esta es una diapositiva de la línea de tiempo. Mostrar datos relacionados con los intervalos de tiempo aquí.
Diapositiva 59 : Esta es una diapositiva de agradecimiento con dirección, números de contacto y dirección de correo electrónico.
Financiamiento del proyecto inmobiliario Diapositivas de presentación de Powerpoint con las 64 diapositivas:
Utilice nuestras diapositivas de presentación de Powerpoint de Financiamiento de Proyectos Inmobiliarios para ayudarlo de manera efectiva a ahorrar su valioso tiempo. Están listos para encajar en cualquier estructura de presentación.
-
Financing of Real Estate Project
-
Agenda for Financing of Real Estate Project
-
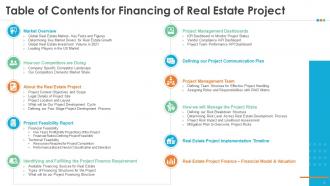
Table of Contents for Financing of Real Estate Project
-
Market Overview
-
Global Real Estate Market Key Facts and Figures
-
Determining Key Market Drivers for Real Estate Growth
-
Global Real Estate Investment Volume in 2021
-
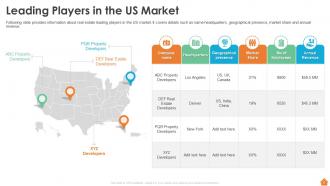
Leading Players in the US Market
-
How our Competitors are Doing
-
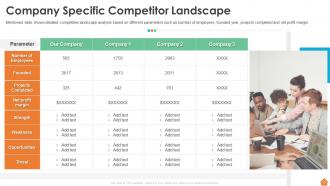
Company Specific Competitor Landscape
-
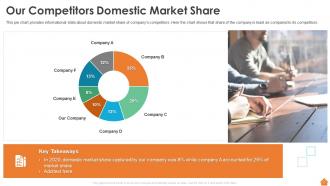
Our Competitors Domestic Market Share
-
About the Real Estate Project
-
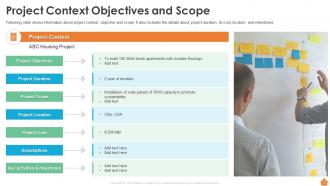
Project Context Objectives and Scope
-
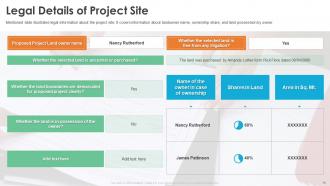
Legal Details of Project Site
-
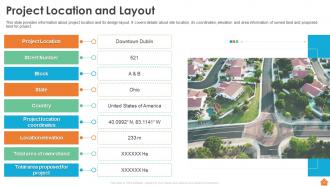
Project Location and Layout
-
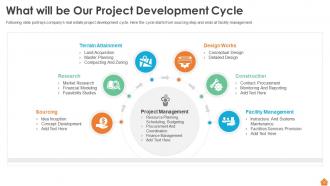
What will be Our Project Development Cycle
-
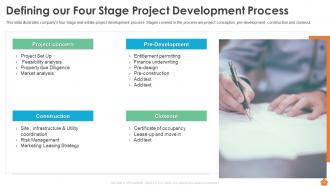
Defining our Four Stage Project Development Process
-
Project Feasibility Report
-
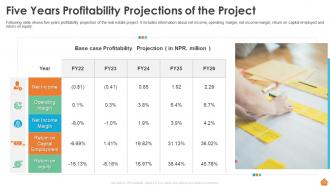
Five Years Profitability Projections of the Project
-
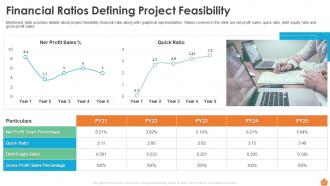
Financial Ratios Defining Project Feasibility
-
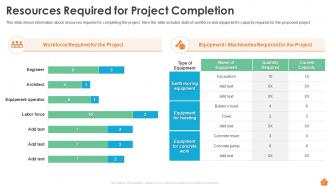
Resources Required for Project Completion
-
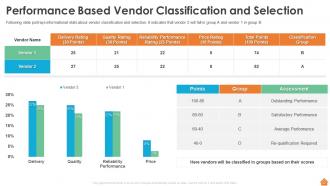
Performance Based Vendor Classification and Selection
-
Identifying and Fulfilling the Project Finance Requirement
-
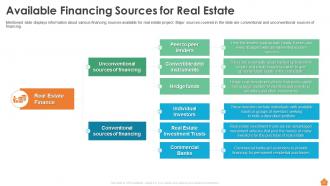
Available Financing Sources for Real Estate
-
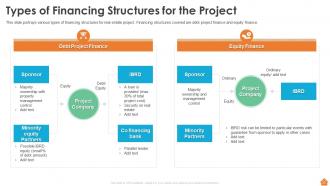
Types of Financing Structures for the Project
-
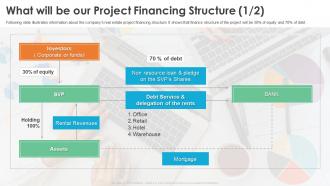
What will be our Project Financing Structure 1 2
-
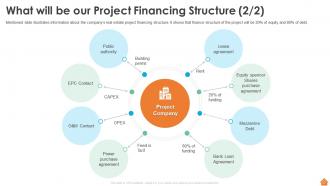
What will be our Project Financing Structure 2 2
-
Real Estate Project Finance Financial Model Valuation Real Estate Project Implementation Timeline
-
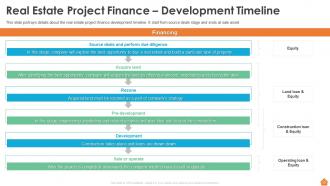
Real Estate Project Finance Development Timeline
-
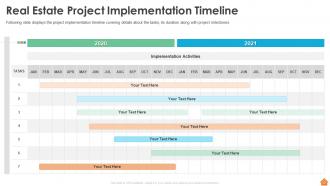
Real Estate Project Implementation Timeline
-
How we will Manage the Project Risks
-
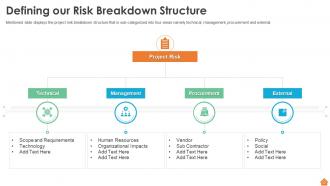
Defining our Risk Breakdown Structure
-
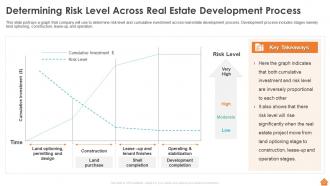
Determining Risk Level Across Real Estate Development Process
-
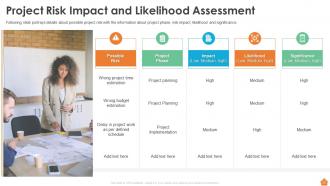
Project Risk Impact and Likelihood Assessment
-
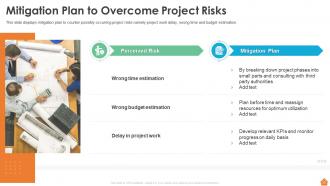
Mitigation Plan to Overcome Project Risks
-
Project Management Team
-
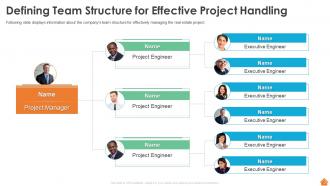
Defining Team Structure for Effective Project Handling
-
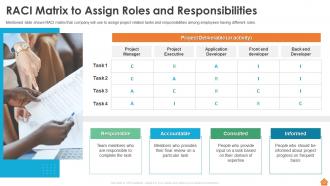
RACI Matrix to Assign Roles and Responsibilities
-
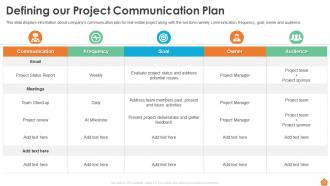
Defining our Project Communication Plan
-
Project Management Dashboards
-
KPI Dashboard to Monitor Project Status
-
Vendor Compliance KPI Dashboard
-
Project Team Performance KPI Dashboard
-
Icon Slide for Financing of Real Estate Project
-
Additional Slides
-
Feasibility Analysis Matrix for Real Estate Project
-
Financing of Real Estate Project
-
About Us
-
Meet Our Team
-
Our Mission
-
Our Target
-
Roadmap
-
Puzzle
-
Financial
-
Mind Map
-
Venn
-
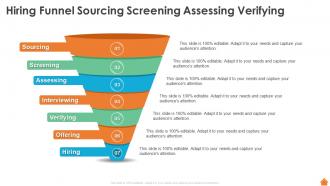
Hiring Funnel Sourcing Screening Assessing Verifying
-
Timeline
-
Thank You
-

-

-

-

-

FAQs for Financing Of Real Estate Project
Interest rates are obviously key - fixed vs adjustable makes a big difference. Down payment size will hit your monthly payments hard, plus you might get stuck with PMI if it's too low. 15-year vs 30-year loans? The monthly payments jump but you save tons long-term (honestly wish I'd known this earlier). Credit score basically determines what doors even open for you. Closing costs can be brutal - like way more than you'd expect. Check the lender's rep too and how fast they actually close. I'd get pre-approved with 2-3 different places so you can compare real numbers.
Hey! So rates mess with your returns in two big ways. Your mortgage payments get more expensive, which obviously cuts into your monthly cash flow. Property values usually drop too since fewer people can actually afford to buy anything. Honestly, it's kind of brutal when rates spike fast like they did recently. But when rates are low? You can borrow more money and property prices tend to go up. My advice - try to time your purchases when rates aren't terrible, and always run the numbers assuming they'll jump another 2-3% just to be safe.
So fixed-rate means your payment stays exactly the same every month - super nice for budgeting. Variable rates start cheaper, which is tempting, but they bounce around with the market. Honestly feels like rolling dice sometimes. You're basically choosing between playing it safe or gambling that rates won't spike. If you're planning to move in a few years anyway, variable might be worth the risk. But if you're the type who loses sleep over money stuff (no judgment - I totally get it), fixed gives you that peace of mind. Really comes down to your situation.
So basically, you put down way less cash but control way more property. Like instead of buying one $200k house outright, you could do 20% down on five houses - now you're making money off $1M in real estate instead of just $200k. Pretty sweet when prices go up, right? But here's the thing - if the market tanks or you can't make payments, you're screwed on a much bigger scale. Honestly though, I'd just start with one property first. Get used to dealing with tenants and maintenance before you go crazy with it.
Look, your credit score is basically everything when it comes to getting good loan terms. Above 740? Lenders will actually fight for you with their best rates. Below that and you're paying more - sometimes way more. I'm talking thousands extra over the loan life, which is honestly insane when you think about it. Even 20 points can make a huge difference. Got time before you need the loan? Pay down those credit cards first and check your report for errors. Trust me, it's worth the wait if your score needs work.
So you've got a few routes here. Conventional loans need like 20-25% down for investment properties - pretty standard stuff. Hard money's insanely expensive but if you need to close fast, it works. There's also DSCR loans which are kinda cool because they look at the property's cash flow instead of your income. Portfolio loans from local banks are worth checking out since they don't sell them off to other lenders. Oh and commercial loans if you're going bigger. Honestly though? I'd hit up some local portfolio lenders first - they're way more flexible than the big guys.
So REITs can actually raise money way easier than if you bought property directly. They issue stocks, sell corporate bonds, get credit lines that we regular people can't access. Pretty unfair honestly. But here's the thing - they have to pay out 90% of their profits as dividends, which is great for us but means they're always hunting for outside money to grow. You'd just use mortgages and whatever cash you have. REITs cost more to finance but you get way better liquidity and don't have all your eggs in one building.
So hard money lenders are basically when you need cash fast but don't mind paying through the nose for it. Think 10-15% interest plus fees - pretty brutal honestly. The upside? Funding happens in days, not weeks, and they care more about the property than your credit score. Perfect for flippers who spot a good deal and can't wait around. Just know you're looking at 6-12 month terms max, so you better flip that house quick or have another way out. I'd only use them when time is everything and the numbers still work after those crazy rates.
Oh man, commercial down payments are rough. You'll need 20-35% minimum, which is crazy compared to residential where you can sometimes get away with just 3-5%. Banks think commercial stuff is way riskier so they want more cash upfront. Your credit matters too, obviously. Some lenders are pickier than others depending on what type of property you're buying. I learned this the hard way when I was looking into it last year - definitely start saving now if you're serious about it because closing day hits different when you need that much cash.
Hey! So you're gonna need a bunch of stuff - recent pay stubs, your last two years of W-2s or tax returns, and bank statements. Also employment verification letters. Credit card statements and any existing loan info too since they want to see your whole financial picture. Once you're under contract, you'll need the purchase agreement and property appraisal. Honestly, start gathering everything now because it's such a pain tracking down old documents - I learned that the hard way. My bank took forever to get me statements from like 18 months ago.
So basically these crowdfunding sites let you pool money with other people to buy real estate you'd never afford alone. You can start with like $500-$1000 instead of needing hundreds of thousands upfront. Pretty crazy that you can invest in some Miami property while sitting in Denver, right? Plus smaller developers don't have to deal with banks taking forever to approve stuff. I'd honestly just check out Fundrise or RealtyMogul first - they'll show you exactly how it works and you can poke around before committing to anything.
Okay so high-leverage financing is basically borrowing a ton of money to buy property - amplifies your gains but also your losses big time. Cash flow becomes your enemy when vacancy rates jump or interest rates go up. You've got way less equity as a safety net, so even small drops in property values can put you underwater on the loan. Trust me, the math gets brutal when you're at 90%+ leverage and suddenly need to cover major repairs or deal with empty units for months. Honestly I'd run some nightmare scenarios first - like what happens if half your units go empty? See if you can actually survive that before diving in.
Residential stuff is super standardized - you know, 30-year mortgages, FHA loans, basic credit checks. Commercial? Total chaos honestly. Banks care way more about the property's income potential and whether you actually know what you're doing. Down payments are bigger, rates suck more, and terms are shorter like 5-10 years. Oh and forget doing it online - you'll need to schmooze with local bankers first. For residential you can just get pre-qualified online no problem, but commercial is all about relationships.
Dude, lenders are getting super creative right now. ARMs are back because fixed rates still suck. Bridge loans and rent-to-own stuff is everywhere too - honestly didn't see that coming a few years ago. Banks tightened up so private lenders are filling the gap, which is actually pretty smart if you can find good ones. Everything's going digital now - closings, AI doing the underwriting, all that. My advice? Don't just stick with traditional banks. Build some relationships with private guys as your backup plan. You'll need options in this market.
Here's what I'd do - grab a spreadsheet and run both scenarios side by side. For the financed option, take your annual cash flow after paying the mortgage and divide that by whatever cash you put down initially. That's your return rate. Then compare it to just buying all-cash (boring but simple, right?). Don't forget about loan fees and interest costs - they add up quick. If your financed return beats what you could make elsewhere by a solid margin, then financing probably makes sense. I mean, cash does feel way safer though.
-
Thank you for offering such helpful pre-designed templates. They are really beneficial to me in my job.
-
Their professional templates are very impressive, even my manager was curious about the source. I am very grateful.