

Diapositivas de presentación de Powerpoint de valoración empresarial





Try Before you Buy Download Free Sample Product
 Impress Your
Audience
 100%
Editable
 Save Hours
of Time


Informe a la gente sobre una dieta saludable con nuestras diapositivas de presentación en PowerPoint de valoración empresarial. Infórmeles de todos los beneficios que se acumulan.
People who downloaded this PowerPoint presentation also viewed the following :
Contenido de esta presentación de Powerpoint
Diapositiva 1 : Esta diapositiva muestra la valoración empresarial en la que puede ingresar el nombre de su empresa.
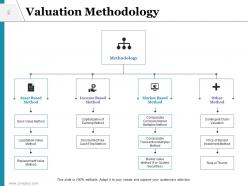
Diapositiva 2 : Esta diapositiva representa la Metodología de valoración basada en varios factores enumerados a continuación utilizando un bonito diagrama: Método basado en activos, Método basado en ingresos, Método basado en el mercado, Otro método, Método de valor en libros, Método de capitalización de ganancias, Método de múltiplos de mercado de empresas comparables, Reclamación contingente Valoración, Método de valor de liquidación, Método de flujo de caja libre descontado, Método de múltiplos de transacciones comparables, Método de precio de inversión reciente, Método de valor de reemplazo, Método de valor de mercado (para valores cotizados), Regla de oro.
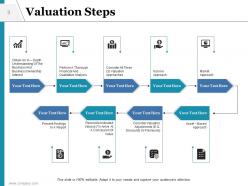
Diapositiva 3 : Esta diapositiva representa los pasos de valoración mediante un bonito diagrama de pasos.
Diapositiva 4 : Esta diapositiva trata sobre las Metodologías de valoración de empresas que cubren factores importantes: Método basado en activos, Método basado en ingresos, Método basado en el mercado, Otro método, Método de valor en libros, Método de capitalización de ganancias, Método de múltiplos de mercado de empresas comparables, Valoración de reclamos contingentes, Liquidación Método de valor, método de flujo de caja libre con descuento, método de múltiplos de transacciones comparables, método de precio de inversión reciente, método de valor de reemplazo, método de valor de mercado (para valores cotizados), regla empírica.
Diapositiva 5 : Esta diapositiva muestra la técnica de flujo de efectivo libre descontado (DCF): conjunto de datos con un fondo e iconos agradables.
Diapositiva 6 : Esta diapositiva ayuda a determinar el flujo de caja libre una vez que ingresa los datos.
Diapositiva 7 : Esta diapositiva muestra los resultados de valoración destacando las categorías principales. La metodología utilizada ayudará a determinar el valor patrimonial y el valor por acción de la empresa.
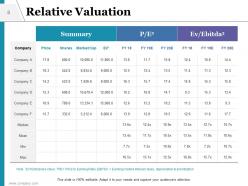
Diapositiva 8 : Esta diapositiva muestra la valoración relativa en formato tabular.
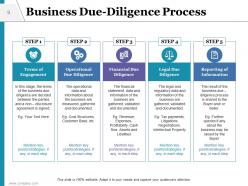
Diapositiva 9 : Esta diapositiva representa el proceso de diligencia debida empresarial explicado en 5 etapas diferentes. PASO 1 Términos del compromiso. En esta etapa, los términos de la diligencia debida comercial se deciden entre las partes y se firma un acuerdo de no divulgación. Mencione los puntos / estrategias clave, si los hay, en cada paso. PASO 2 Debida diligencia operativa. Los datos operativos y la información sobre el negocio se miden, recopilan y documentan. Mencione los puntos / estrategias clave, si los hay, en cada paso, por ejemplo: estructuras de costos, base de clientes, etc. PASO 3 Diligencia debida financiera El estado financiero, los datos y la información de la empresa se recopilan, validan y documentan. Mencione los puntos / estrategias clave, si los hay, en cada paso, por ejemplo: Ingresos, Gastos, Rentabilidad, Flujo de caja, Activos y Libalidades PASO 4 Debida Diligencia Legal La información y los datos legales y regulatorios de la empresa se recopilan, validan y documentan. Mencione los puntos / estrategias clave, si los hay, en cada paso. Por ejemplo: pagos de impuestos, litigios, registros, propiedad intelectual PASO 5 Reporte de información El resultado del proceso de diligencia debida comercial se comparte con el Comprador y / o el Vendedor. Mencione los puntos / estrategias clave, si los hay, en cada paso. Por ejemplo: El Comprador puede plantear más consultas, si las hay, sobre el negocio.
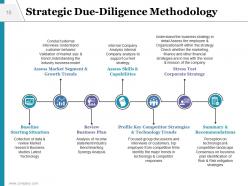
Diapositiva 10 : Esta diapositiva representa la Metodología de Debida Diligencia Estratégica basada en diferentes criterios. Línea de base, situación inicial, evaluación del segmento de mercado y tendencias de crecimiento, revisión del plan de negocios, evaluación de habilidades y capacidades, perfil de estrategias de competidores clave y tendencias tecnológicas, estrategia corporativa de prueba de estrés, resumen y recomendaciones.
Diapositiva 11 : esta diapositiva muestra la diapositiva de iconos que tiene un conjunto adicional de iconos.
Diapositiva 12 : Esta diapositiva recuerda la pausa para el café de 10 minutos. Puede modificar la diapositiva según sea necesario.
Diapositiva 13 : Esta diapositiva muestra Gráficos y tablas. Esto indica que las diapositivas adicionales tratan sobre gráficos y tablas. Puede cambiar el título.
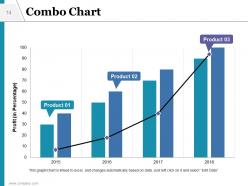
Diapositiva 14 : Esta diapositiva representa un gráfico combinado y está diseñada con la combinación de un gráfico de líneas y un gráfico.
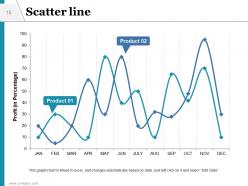
Diapositiva 15 : Esta diapositiva representa el gráfico de dispersión que se muestra con un gráfico de líneas.
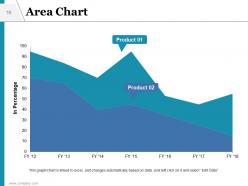
Diapositiva 16 : esta diapositiva representa el gráfico de área de la pila. Este gráfico está vinculado a Excel y cambia automáticamente en función de los datos. Simplemente haga clic en él y seleccione "Editar datos".
Diapositiva 17 : esta diapositiva dice Diapositivas adicionales. Puede cambiar el título y el contenido de la diapositiva.
Diapositiva 18 : Esta diapositiva representa la diapositiva Nuestra misión. Puede escribir la misión, la visión y el objetivo de su empresa.
Diapositiva 19 : Esta diapositiva representa sobre nuestro equipo. Puede ingresar el nombre, la designación y las imágenes de los miembros del equipo.
Diapositiva 20 : Esta diapositiva representa Acerca de nosotros y puede ingresar detalles importantes de su empresa.
Diapositiva 21 : Esta diapositiva representa Nuestro objetivo. Puede ingresar el objetivo de su empresa y también puede cambiar la imagen.
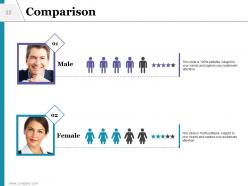
Diapositiva 22 : Esta es una diapositiva de comparación representada mediante el uso de bonitos iconos e imágenes.
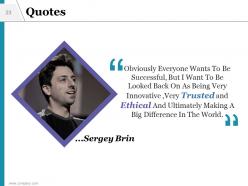
Diapositiva 23 : esta diapositiva representa citas. También puede utilizar cualquier otra cotización.
Diapositiva 24 : esta diapositiva se puede usar para ingresar texto usando el diagrama de Venn.
Diapositiva 25 : Esta última diapositiva es la diapositiva de agradecimiento. Puede escribir la dirección de su empresa, número de contacto y dirección de correo electrónico.
Diapositivas de presentación de PowerPoint de valoración empresarial con las 25 diapositivas:
Agregue a la ventaja que ya tiene con nuestras diapositivas de presentación de PowerPoint de valoración empresarial. Aumentará su ventaja.
-
Business Valuation
-
Valuation Methodology
-
Valuation Steps
-
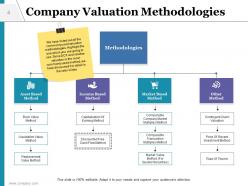
Company Valuation Methodologies
-
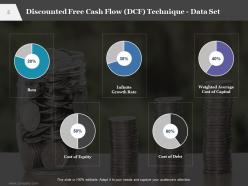
Discounted Free Cash Flow DCF Technique Data Set
-
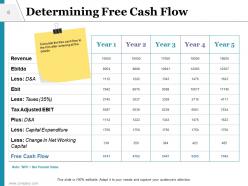
Determining Free Cash Flow
-
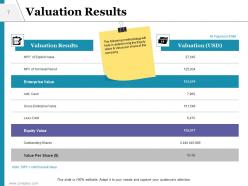
Valuation Results
-
Relative Valuation
-
Business Due Diligence Process
-
Strategic Due Diligence Methodology
-
Icon Slide
-
Coffee Time Break
-
Graphs And Charts
-
Combo Chart
-
Scatter line
-
Area Chart
-
Additional Slides
-
Our Mission
-
Our Team
-
About Us
-
Our Goals
-
Comparison
-
Quotes
-
Venn
-
Thank You Slide
FAQs for Business Valuation
Okay so there are basically three ways to value a company. Asset-based is simple - what they own minus debts. Doesn't tell you much about growth potential though. Then there's income-based stuff like DCF that tries to predict future cash flows, but honestly those projections can be total guesswork sometimes. Market-based compares your company to similar ones that sold recently. Each method spits out different numbers, which is why most people use all three and try to find a reasonable middle ground. Just pick whatever makes sense for your industry and situation.
Market conditions are basically like a volume knob for what your business is worth. Good times? Valuations go crazy high. Bad times mean even decent companies take a hit on their value. Industry multiples shift around, investors get either greedy or scared, and comparable sales tell the whole story. During bull runs everyone's tossing money everywhere and overpaying for everything - honestly it's kind of wild to watch. Bear markets flip that script completely. Buyers turn into total cheapskates wanting discounts for any little risk they can find. Smart move is timing your valuation right, or if you're in a rough patch, just wait it out.
You absolutely need financial statements to value any company - there's no way around it. They show you historical performance so you can spot revenue trends, profitability patterns, and cash flow health. The income statement helps you project future earnings, balance sheet shows assets and liabilities, cash flow statement reveals actual cash generation. Honestly, audited statements are way better if you can get them - garbage data in, garbage valuation out. I learned that the hard way on a deal last year. These statements are basically your raw ingredients for whatever valuation method you're using.
Dude, intangible assets are honestly huge for valuations. Patents, trademarks, customer lists, your proprietary software - this stuff often makes up most of a company's real worth nowadays. Apple's brand value alone is insane when you think about it. The annoying thing? Regular accounting totally misses their actual value. You'll need income projections or market comps to figure out what they're really worth. Tech companies especially - their intangibles can dwarf everything else on paper. Don't ignore them when you're crunching numbers because that's where the money actually is.
Honestly, cash flow projections are like the foundation of any decent business valuation. They tell you what a company will actually spit out in cash over time - and that's what really matters to investors. DCF models use these to discount future flows back to today's value. Here's the thing though: your assumptions about growth, margins, and capital needs have to be realistic. Garbage in, garbage out, you know? I've seen way too many overly rosy projections that don't match reality. Build conservative assumptions you can actually defend rather than pie-in-the-sky numbers.
So here's the deal - industry trends basically make or break your valuation. Growing sectors like AI or renewable energy? You'll get crazy high multiples because everyone's betting on future growth. Meanwhile, traditional retail and print media are getting hammered even when their current numbers look decent. Buyers aren't just paying for what you are now, they're gambling on what you'll become. Honestly, it's kind of unfair but that's how the game works. Before any valuation meeting, dig into where your industry's headed and have a solid story about how you'll adapt. The narrative matters almost as much as the numbers.
Dude, biggest mistake is using crappy or old financial data - total garbage in, garbage out situation. Wrong valuation method for your industry will screw you over too. Don't just stick to one approach; try a few different methods to see if they line up. Market conditions change everything, so check recent sales in your area. Oh, and if it's your own business? You're probably way too emotionally invested to be objective about it. Honestly happened to my cousin last year - he thought his restaurant was worth twice what it actually was. Get someone else to look at your numbers, especially your future projections. Fresh perspective helps tons.
Honestly, there's a couple ways to tackle this. Add up your assets minus debts first - that's your baseline. Finding comparable business sales is a nightmare though, good luck with that one. If you've got steady cash flow, try the income method - take your annual earnings and multiply by whatever multiple your industry uses. I'd run at least two different approaches since they'll probably give you different numbers. And if this is for anything serious like selling or divorce stuff, just bite the bullet and hire a real appraiser. Trust me on that one.
Hey! Investors care about your team first - can you actually pull this off? Market size is big too, but honestly, growth potential matters more than pure size. They'll want to see your revenue model and whatever traction you've got so far. Defensibility against competitors is huge. Do you have any kind of moat or advantage? I always think the competitive landscape question trips people up the most. Your startup's stage obviously changes what they're looking for. Bottom line - nail these points in your pitch deck before you walk into those meetings.
Look, economic indicators basically control how much people think your business is worth. Good GDP growth, low unemployment, stable inflation? Investors get excited and pay more. But flip that - interest rates spike or consumer confidence tanks - and suddenly everyone's way more cautious about valuations. Track stuff like interest rates and industry metrics because timing matters big time when you're trying to sell or raise money. It's honestly like reading the room before making your pitch. Nobody wants to admit it, but market sentiment drives so much of this stuff.
So there's three ways to figure out what your business is worth. Asset-based just looks at what you own minus debt - pretty straightforward balance sheet stuff. Then there's income-based, which takes your future cash flows and brings them back to today's dollars (honestly my go-to for companies making decent money). Market-based compares you to similar businesses that sold recently. Here's the thing though - you really should use at least two methods. Asset approach might totally miss intangible stuff, and good luck finding truly comparable companies for the market method. I'd start with whatever fits your industry best.
Honestly, get your books cleaned up first - like actually clean, not just "looks fine to me" clean. Three years of solid financial statements are non-negotiable. I watched a buddy's sale almost fall through because his QuickBooks looked like a dumpster fire. Gather all your contracts, employee stuff, customer agreements too since they'll want to see everything. Oh, and try to make the business run without you constantly hovering - that's huge for valuation. Start this whole mess at least 6 months early. Trust me, last-minute scrambling just makes you look unprepared and desperate.
Dude, M&A stuff can really bump up what your company's worth. Strategic buyers usually pay way more than financial ones - like 20-40% more - because they can actually use those synergies (cost cuts, bigger market reach, whatever). Industry consolidation creates this weird bidding war effect where everyone's competing. Honestly, even rumors about deals can move your valuation up. Wild how that works. If you're thinking about selling, try timing it when there's buzz about acquisitions in your space. Those strategic premiums are no joke - they'll pay extra for synergies that financial buyers can't really capture.
Oh yeah, this stuff matters way more than people think. C-corps usually get better valuations since investors get them easily - no weird tax pass-through headaches. LLCs? Some investors literally won't touch them because of the K-1 nightmare (my accountant still complains about mine from 2019 lol). Your structure also changes how easy it is to transfer ownership and run things day-to-day. Buyers definitely notice. If you're thinking exit or fundraising, change it now - I've seen deals get messy when you're trying to restructure mid-negotiation. Way harder than doing it upfront.
BizComps, Pratt's Stats, and DealStats are probably your best bet for transaction multiples - just know they're expensive unless you already have access. For public comps, S&P Capital IQ is solid, or honestly even Yahoo Finance works fine for basic stuff. Trade associations publish some really good industry studies too that people overlook. I'd check what your firm already pays for first since those subscriptions add up fast. If you're gonna be doing valuations regularly though, BizComps is probably worth it. Start there and see what gaps you still have.
-
Colors used are bright and distinctive.
-
Informative presentations that are easily editable.